
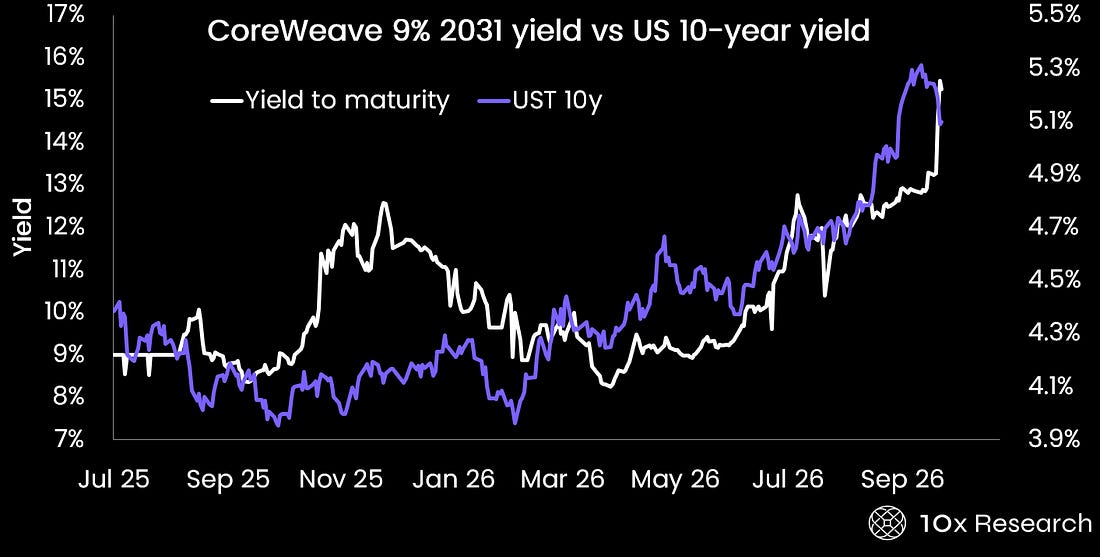
Since September 22, Bitcoin is down 5%, while the miners we track are down 28% to 53%. The cause is CoreWeave. Its bonds yield over 15%, its five-year CDS hit a record 1,194bp on October 15, and it planned $21–25bn of capex for the second half of 2026 after free cash flow of negative $5.7bn in Q2. The miners copied CoreWeave’s model of long leases to AI labs financed with debt, and they now trade on its credit, not on Bitcoin. The stress shows up in CoreWeave’s bonds, but the miners’ shareholders have taken the losses. This report sets out how the repricing happened so quickly: CoreWeave’s balance sheet, its customer and contract risks, the September convertible that marked the top of the rebound, and why funding the miners’ next megawatts now costs much more. We close with what portfolio managers should watch before trying to call a bottom.
Subscribe to 10x Research Market Updates to unlock the rest.Become a paying subscriber of 10x Research Market Updates to get access to this post and other subscriber-only content. A subscription gets you:
|




No comments:
Post a Comment