Welcome to the Free edition of How They Make Money. Over 300,000 subscribers turn to us for business and investment insights In case you missed it: The Token EconomyHeadlines are fixated on AI bubble skepticism, while NVIDIA’s numbers tell a story of a new world being built. CEO Jensen Huang believes we officially moved past the era of experimental training and entered the era of the agentic inflection:
Huang is framing NVIDIA’s chips not as a capital expense, but as the direct raw material (tokens) required for customers to make money. The latest quarter highlights three structural pillars:
Let’s break down the quarter. Today at a glance:
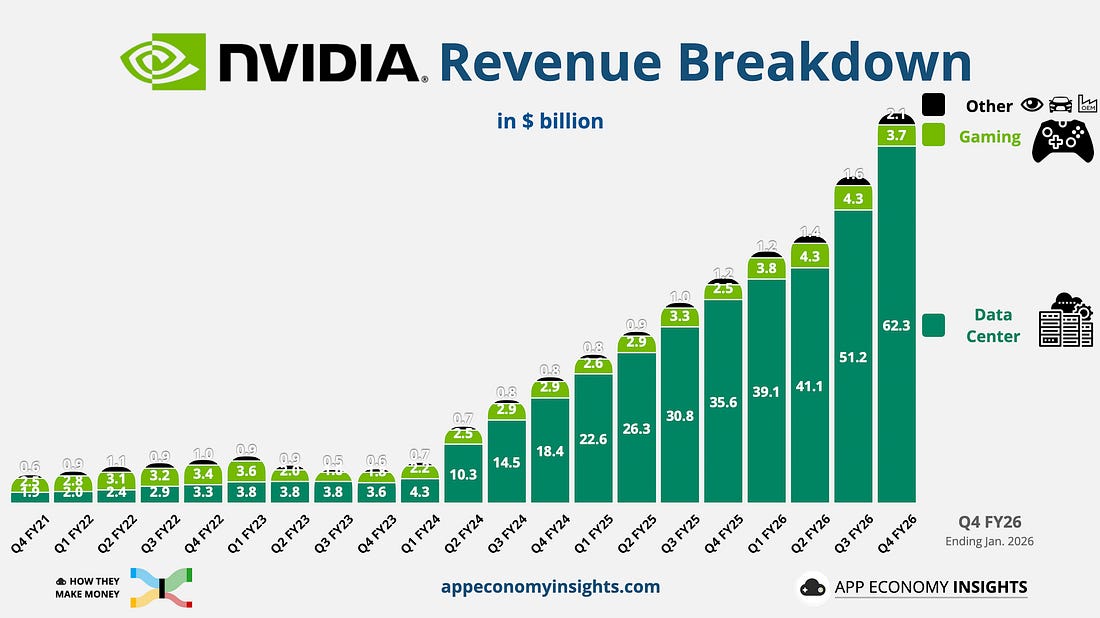
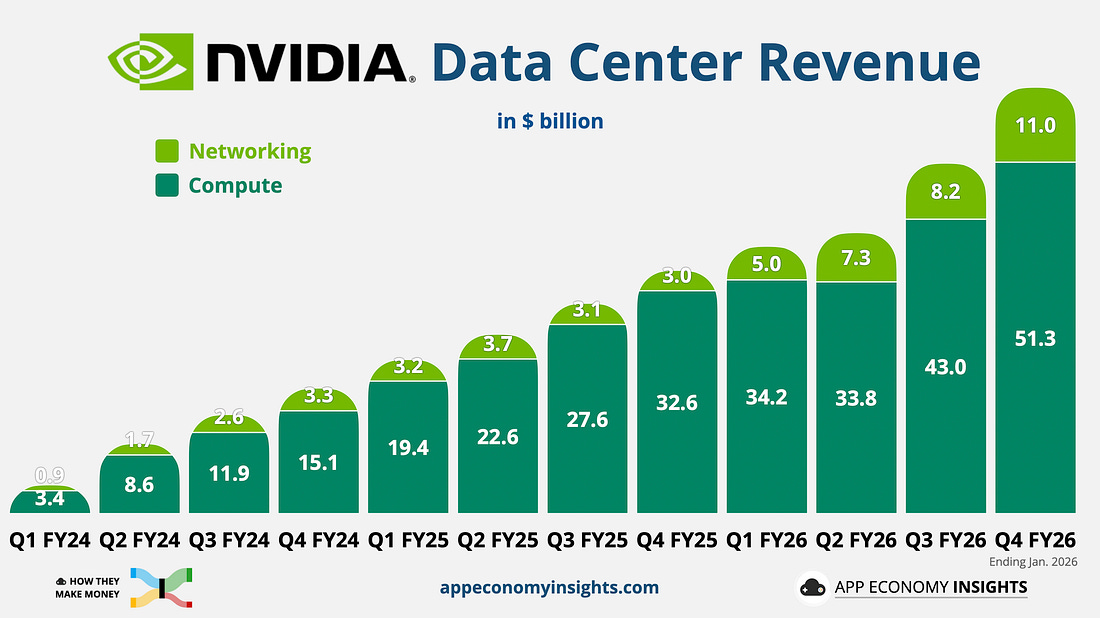
1. NVIDIA Q4 FY26NVIDIA’s fiscal year ends in January, so they just reported Q4 FY26. Data Center revenue remains off the charts, as illustrated below.
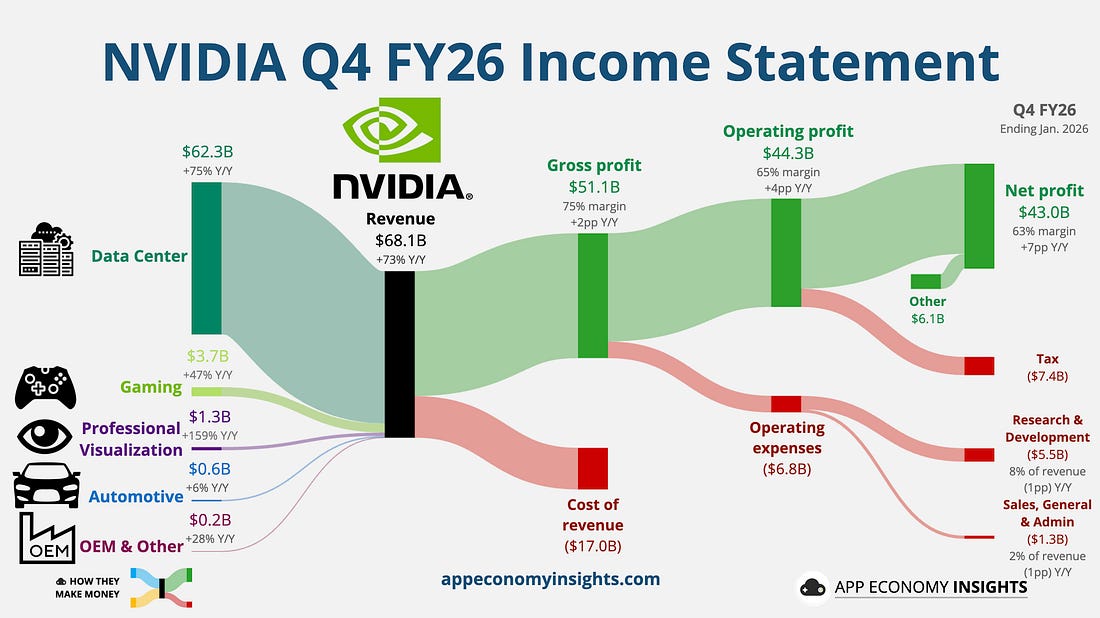
Income statement:
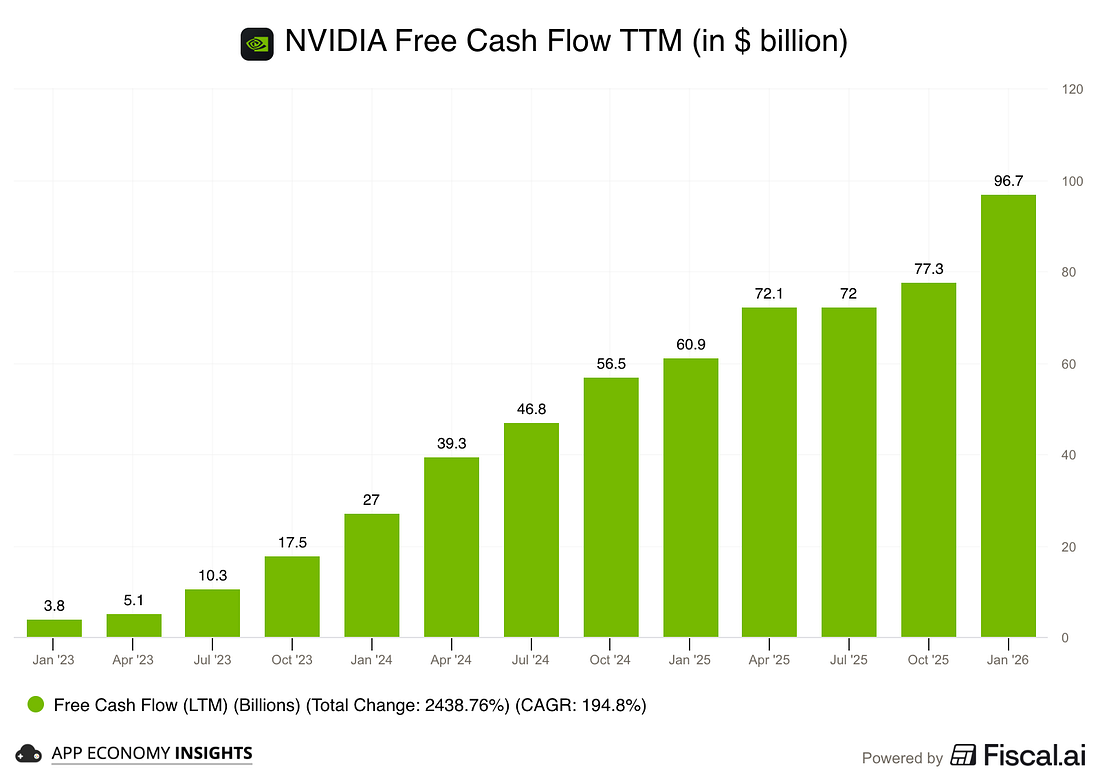
Cash flow:
Balance sheet:
Q1 FY27 Guidance:
So, what to make of all this?
2. Business highlights🔄 Circular Economy CritiqueThe market is increasingly focused on the cozy relationship between NVIDIA and its largest customers. With nearly $97 billion in annual free cash flow, NVIDIA is becoming the venture capitalist of the AI age.
By participating in OpenAI’s latest $30 billion round and deepening ties with Anthropic and CoreWeave, NVIDIA ensures that the most advanced AI models remain optimized for CUDA. Critics argue that NVIDIA is funding its own customers. Jensen Huang defended this by highlighting the diversity of the customer base. Hyperscalers now account for only 50% of revenue, and growth is shifting toward sovereign AI and enterprise ISVs. The circular risk is diluted as the ecosystem broadens. He also doubled down on the idea that customers must keep spending to grow. It captures the tension of this moment. NVIDIA sees a new industrial revolution, while some on Wall Street see a CapEx binge. ↗️ AMD’s New ShareholdersA more immediate threat emerged recently, as some of NVIDIA’s largest customers became shareholders in a competitor. Meta just announced a multi-generation agreement worth more than $100 billion to deploy up to 6 gigawatts (GW) of AMD compute capacity. To secure this capacity, AMD issued Meta performance-based warrants for up to 160 million shares—roughly a 10% equity stake in AMD. It is a carbon copy of the OpenAI-AMD pact signed in late 2025, which also included a 6 GW commitment and a 10% equity incentive. By aligning their financial interests with AMD, two of NVIDIA’s most important allies are now directly incentivized to see AMD’s MI450 architecture succeed. For every gigawatt they deploy, they not only solve their supply chain bottleneck, but they also potentially unlock billions in capital appreciation from their AMD holdings. They are ecosystem partners with a vested interest in a multi-polar GPU market. 🇨🇳 China/Trump WildcardThe market is valuing NVIDIA as if China is permanently zero. That embeds an option into the stock. The Trump administration’s decision to allow small-scale H200 shipments comes with a US inspection requirement and a 25% tariff. This effectively makes NVIDIA chips the most expensive way to build AI in China. CFO Colette Kress was clear that they are guiding for $0 revenue from China Data Center compute. This conservative guidance means any surprise approval or easing of these inspections represents an upside. NVIDIA is currently winning without China. 3. Key quotes from the earnings callCheck out the earnings call transcript on Fiscal.ai here. CEO Jensen Huang:On the agentic shift:
The latest catalyst is the shift from chatbots to autonomous agents that “run for minutes to hours” and consume massive amounts of compute. On the “Dielet Tax” and architectural integrity:
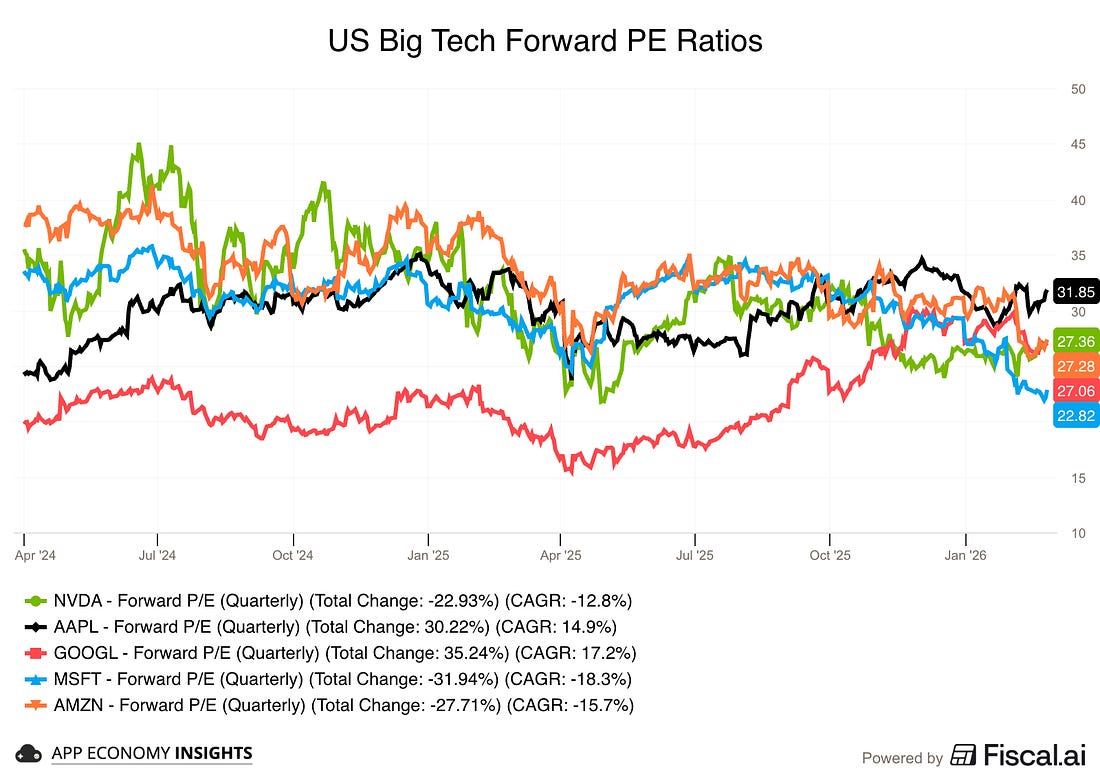
Jensen is defending NVIDIA’s monolithic design (single piece) as a physical advantage in power efficiency that competitors using multi-chiplet designs can’t easily match. His bet is that architectural purity beats modular flexibility at hyperscale. 4. What to watch moving forwardNVDA has been mostly flat in the past 6 months, a period of consolidation. The latest 13F filings for Q4 2025 showed that some funds were still buying, such as Altimeter and Atreides. The stock remains one of the most widely held names, although many funds are still underexposed relative to its nearly 8% weight in the S&P 500. At ~27x forward earnings, NVIDIA trades mostly in line with the rest of Big Tech. But with EPS surging 67% Y/Y, you could certainly argue it looks cheap. NVIDIA’s growth is supply-constrained. That means quarter-to-quarter noise matters less than understanding how long this cycle can run and what the business looks like when demand normalizes.
If you’re a regular reader, you already know the stakes:
In a token economy, efficiency is profit. That’s the battlefield NVIDIA intends to dominate.
That’s it for today! Happy investing! Want to sponsor this newsletter? Get in touch here.Thanks to Fiscal.ai for being our official data partner. Create your own charts and pull key metrics from 50,000+ companies directly on Fiscal.ai. Save 15% with this link. Disclosure: I own AAPL, AMD, AMZN, GOOG, META, and NVDA in App Economy Portfolio. I share my ratings (BUY, SELL, or HOLD) with App Economy Portfolio members. Author's Note (Bertrand here 👋🏼): The views and opinions expressed in this newsletter are solely my own and should not be considered financial advice or any other organization's views. I would love to hear your feedback! Reply to this email to reach out to me with questions or suggestions. If you enjoyed today's newsletter, please share it with your friends and family! You’ll earn rewards if they subscribe. You’re a free subscriber to How They Make Money. For the full experience, become a Premium subscriber.
|
Friday, February 27, 2026
🤖 NVIDIA's Tokenomics





Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment