Welcome to the Free edition of How They Make Money. Over 260,000 subscribers turn to us for business and investment insights. In case you missed it: 🎉 Welcome to 2026New year, same obsession: How market leaders actually make money. While the internet is busy making bold predictions and hot takes, we’re starting the year the only way we know how: By following the money. 💰 Today at a glance:
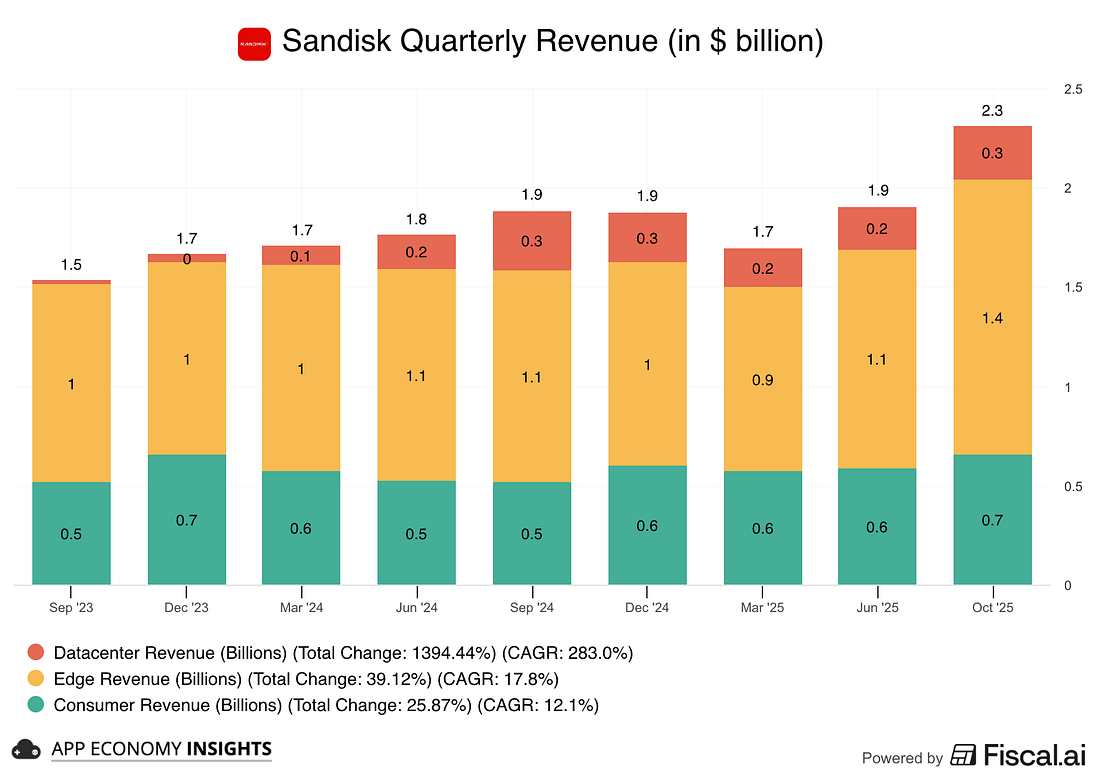
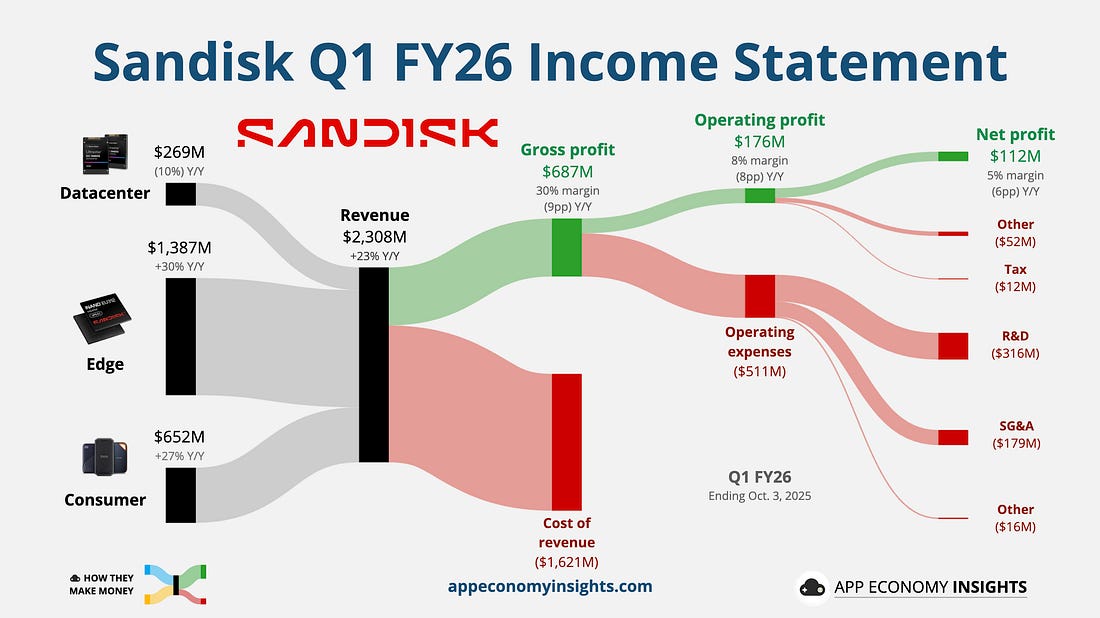
📈 Sandisk Absolutely Crushed 2025If you spent 2025 watching only the Mag 7, you missed one of the big stories of the year. The best-performing stock in the S&P 500 wasn’t a hyper-scaler or an LLM designer. It was a company that didn’t even exist as an independent entity at the start of the year. Sandisk (SNDK) delivered a staggering ~594% return since its spinoff from Western Digital (WDC) in February 2025. For years, Western Digital’s stock was dragged down by a conglomerate discount, trying to run a legacy Hard Drive business and a high-growth Flash business under one roof. The spinoff finally freed Sandisk to be valued on its own merits. It became a pure-play on the next phase of the AI buildout. But a nearly 7x surge in under a year requires more than just a corporate reshuffle. It requires a fundamental misunderstanding by the market of how a company makes money. That misunderstanding was amplified by years of NAND price cyclicality, which trained investors to treat every storage rally as temporary. It’s not just USB drivesMany investors still associate Sandisk with the little SD card in their camera. While that Consumer segment still provides cash flow, it’s no longer the engine.
Sandisk makes NAND Flash memory, the essential technology for fast, non-volatile storage. Their revenue is now driven by three distinct pillars:
AI Multiple ValuationSandisk’s 2025 story was all about multiple expansion. The market stopped valuing Sandisk like a single-digit multiple NAND supplier and began pricing it closer to AI infrastructure peers with durable demand visibility. In early 2025, the market valued Sandisk like a commodity hardware seller (a low P/E multiple). By mid-year, the narrative shifted. Investors realized that if AI is the new electricity, high-speed storage is the copper wire beneath it. Invisible, essential, and impossible to scale without. Sandisk was “re-rated” from a boring hardware stock to critical AI infrastructure.
This re-rating was so powerful that the stock ripped higher even as gross margins compressed. Why? Investors recognized that Sandisk was executing a deliberate land grab, accepting near-term margin pressure as it ramps enterprise volumes and secures long-term hyperscaler relationships with data centers building out their AI architecture for the next decade. What’s the moat? Sandisk’s advantage relies on the high switching costs of the "Qualification Cycle." In the AI era, hyperscalers cannot simply swap out storage components on a whim. Drives must undergo grueling 6-to-12-month testing regimens to ensure they don't cause latency spikes that idle expensive GPUs. Once Sandisk wins a socket and becomes the "Plan of Record," it locks in that revenue for the server's entire 3-to-5-year lifecycle. Furthermore, while competitors like Samsung are prioritizing HBM capacity for GPUs, Sandisk has capitalized on the less crowded lane of Enterprise SSDs, using specialized controllers and firmware to turn what used to be a commodity component into a sticky, essential layer of the AI infrastructure stack.
🧠 Meta Bets on AI Startup ManusMeta Platforms just made another bold AI move, agreeing to acquire Manus for more than $2 billion, a deal reportedly agreed in just 10 days. It might sound like a steep price, but Manus isn’t a typical chatbot. It’s a general-purpose AI agent designed to plan tasks, pull in tools, and deliver finished work. Think research reports, code, data analysis, or even websites, with minimal human input. Manus was founded in China in 2022 and later moved to Singapore. It officially launched its agent in March 2025. Key numbers
That puts Manus in rare territory for enterprise software adoption. Meta plans to continue selling Manus as a standalone product while integrating its agent capabilities across Meta’s ecosystem: Facebook, Instagram, WhatsApp, ads, and AI hardware. Why it mattersMeta has world-class models and massive distribution, but it has lagged peers like ChatGPT and Gemini in real, task-oriented AI applications. Manus fills that gap immediately. Instead of waiting years to build an agent platform from scratch, Meta is buying:
It also gives Meta a path to meaningful AI revenue beyond ads.
🤖 NVIDIA + Groq: The $20B DealIn a move that stunned Wall Street over the holiday break, NVIDIA announced a definitive agreement to pay $20 billion in cash to license the technology and hire the core engineering team of AI chip startup Groq. This is not a traditional acquisition. Groq will continue to exist as an independent entity (renamed GroqCloud), led by former CFO Simon Edwards. However, NVIDIA is effectively absorbing Groq’s “soul”—its proprietary LPU (Language Processing Unit) patents and its visionary leadership, including founder Jonathan Ross (creator of the Google TPU). Why now? To understand this deal, you have to look at the market shift that defined late 2025. We recently crossed a tipping point known as the Inference Flip. Global revenue from using AI models (inference) has officially surpassed the revenue from building them (training). While NVIDIA’s GPUs are the undisputed kings of training (massive throughput), they have a vulnerability: Latency.
By securing Groq’s technology, NVIDIA solves its only real weakness: real-time, low-latency inference for agents and voice AI. What it means:
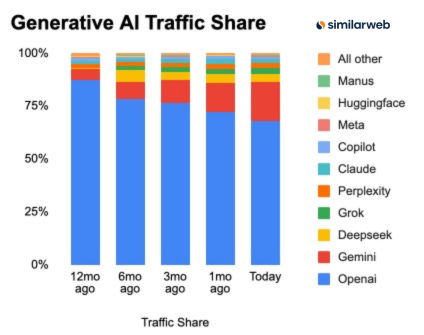
🔎 Gemini’s Very Good YearFor most of 2024, the GenAI story looked simple: ChatGPT dominated, everyone else scrambled. 2025 quietly complicated that narrative. Released on Christmas Day, new data from Similarweb tells one of the most important AI stories of the year:
The shift comes down to distribution. Gemini now sits inside Google’s core products, including Search, Chrome, Android, and Workspace. It’s turning default placement into habitual usage. When AI lives where people already spend their time, adoption follows naturally. Two signals stand out from SimilarWeb’s data:
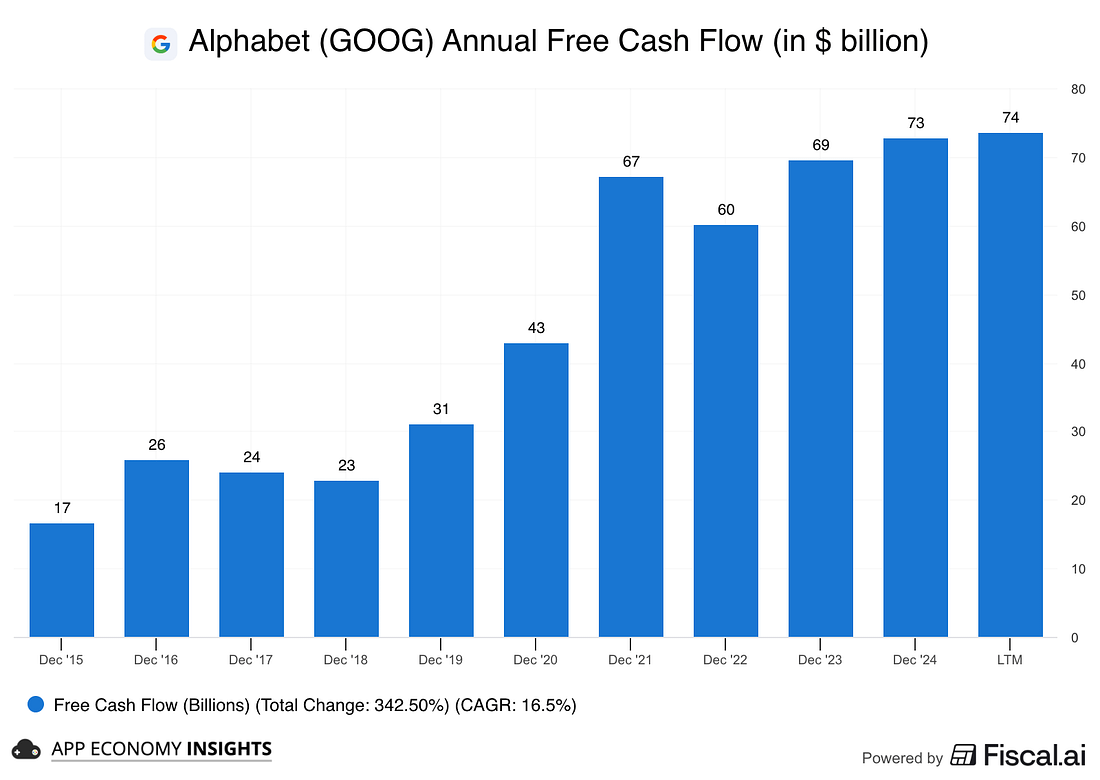
Gemini is the only product meaningfully taking share, and it’s doing so via Google distribution and defaults. As model quality converges, power users might show little loyalty to a single interface. They switch to whatever is cheapest, fastest, or already embedded in their workflow. That challenges the idea of a lasting moat at the AI interface layer. OpenAI doesn’t expect to be profitable until 2030 and, according to Deutsche Bank, could burn more than $140 billion in cumulative negative free cash flow before getting there. Google’s parent Alphabet, by contrast, generated $74 billion in free cash flow over the past 12 months, even after heavy AI investment. That asymmetry matters.
That's it for today. Happy investing! Want to sponsor this newsletter? Get in touch here.Thanks to Fiscal.ai for being our official data partner. Create your own charts and pull key metrics from 50,000+ companies directly on Fiscal.ai. Save 15% with this link. Disclosure: I own GOOG, META, and NVDA in App Economy Portfolio. I share my ratings (BUY, SELL, or HOLD) with App Economy Portfolio members. Author's Note (Bertrand here 👋🏼): The views and opinions expressed in this newsletter are solely my own and should not be considered financial advice or any other organization's views. I would love to hear your feedback! Reply to this email to reach out to me with questions or suggestions. If you enjoyed today's newsletter, please share it with your friends and family! You’ll earn rewards if they subscribe. You’re a free subscriber to How They Make Money. For the full experience, become a Premium subscriber.
|
Friday, January 2, 2026
📈 The Top Stock in 2025






Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment