Disclaimer: The content on this website is for informational and educational purposes only and is not created to meet your personal financial situation. Nothing should be considered as investment advice or as a guarantee of profit. You are advised to consult with your financial advisors to discuss your investment options and whether it would be a suitable investment for your personal needs. The information used in this publication is from sources that are believed to be reliable but the accuracy cannot be guaranteed. It may include some errors, please make sure to do your due diligence. The opinions expressed are those of the author and the author only. These opinions are subject to change without prior notice. Disclosure: The author may own shares in companies mentioned in this article as of 14 January 2026. The security could be sold at any point in time without prior notice. I’ve had some time during the year end to skim through the Shikiho (aka the Japan Company Handbook) and reorganise my ever growing watchlist of interesting companies. Whilst the Japanese market has been on a run recently, I still feel there are some really interesting opportunities in less-covered stocks. Today I wanted to share 5 summaries of my thoughts on companies that looked interesting at a high level and most of them trading at reasonable valuations. (In my opinion). As always, some ideas are free! :) For a change, I talk about several slightly more liquid names than the usual. I’ve tried to look a little more broadly, including things like:
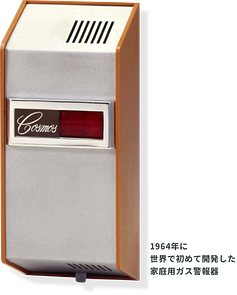
I’m also thinking about creating a ‘live’ watchlist/stocks of interest page on the Substack that I can occasionally update. There are so many interesting ideas I want to write about but not enough time. So I figured it would be fun if my readers just get a head start on it! Anyways Let me know your thoughts on this in the comments. 1. MEEQMEEQ’s leading position as a MVNE/IoT connectivity provider is set to see double-digit growth for the forseeable future. In particular, as the IoT component drives further growth as more companies try to capture ‘real world’ data for their AI Data sets, this should drive margins for the business. Their MVNE segment could also accelerate given they have been gradually phasing out one very large customer - this is coming to an end and the underlying business looks like it may continue to grow strongly, especially as their MVNE as a subscription is gaining interest. The valuation looks undemanding based on these growth dynamics. (although it’s gone up since I started writing…) This is a peculiar business that operates in the connectivity space. In short, the company procures the internet connectivity from the 3 (soon to be 4) main carriers (i.e. MNOs) in Japan. With this MEEQ provides it’s customers a solution to purchase + manage their connectivity (i.e. multiple lines) for their specific needs and use cases through their platform.. It’s best that I try to explain it with their 2 operating segments. MVNE (Mobile Virtual Network Enabler): The company sells Mobile network connectivity to MVNO’s (Mobile Virtual Network Operators) who run their own branded mobile telecom service. The customer concentration is high with the 2 main customers representing a majority of revenues (Kabu&Peace and Neuromobile). The company also recently started “MVNE as a Service” which provides a full service including back office capabilities - i.e. infrastructure some customers simply don’t have and are too expensive to build out. IoT: This business provides customers with the ability to connect and manage the connectivity of all IoT devices. For example, this can be anything from security cameras, payment terminals, or production machinery. Basically, anything that requires connecting to the internet to send data back to the customer’s data warehouse. Here, MEEQ provides a one-stop shop to manage the connectivity of all your devices, of which there can be many, in one place. As you can imagine, given both are tied to a monthly subscription of SIM Cards making this a highly recurring business model. Churn for MVNE is similar to a typical mobile carrier (i.e. low), but also for the IoT segment the churn is even lower because churn only happens when a device is taken out of commission. The synergies between the two is that the fundamental direction of information flow on the networks. For the MVNE business, the ultimate users are individuals on their phone’s, meaning such data flow is focused on ‘downloading’. On the other hand, IoT customers are typically corporations with large fleets of machinery like drones, security camera’s etc to relay data back home. This in turn has a large weight on ‘uploading’. As telecom providers don’t sell download/upload bandwidth separately, MEEQs two segments provide efficient use of telecom services by filling up capacity for both. This leads to efficient capacity utilization which leads to a cost competitiveness others can’t achieve unless you’re able to build both at scale. Currently, the business has native, secure connectivity with NTT Docomo, KDDI and Softbank’s core network. This matters because the use cases may involve sending sensitive information and you don’t want to do that in an unsecure environment. Such native connectivity is also hard to do and requires significant upfront costs. So far only one other company has connectivity to 3 carreirs but they have a completely different business. Internet Initiatives Japan (IIJ) also has NTT and KDDI as carriers but given they are both shareholders it is unlikely they can win Softbank or Rakuten. The advantage of having multiple carriers is that some providers have better connections depending on the location. So by being able to provide 3 (and soon 4), the customers of MEEQ can mix and match depending on their needs. The company is expected to soon sign on Rakuten as well. On the MVNE side, they’re seeing an increasing number of companies looking to start an MVNO i.e. their self-branded SIM cards, as they look to find an additional touch point with customers and provide rewards. (An example is JAL, which has their JAL mobile, which helps customers accumulate miles). MEEQ is now looking to grow via MVNE ‘as a service’ which basically means in addition to simply the connections, MEEQ can provide the operational/back office needs surrounding it, which can be complex (including legal stuff). The company wants to sustain a 10-15% topline CAGR on the MVNE side, whilst the IoT is lumpier, it seems a sustained double-digit growth could be a realistic possibility given the inherent tailwinds for connectivity. With margin expansion coming from the growing contribution of the IoT segment. Maybe a long shot here is that with “Physical AI” i.e. autonomous machines becoming a theme in Japan, MEEQ may just fall into that from their IoT, but this, I’m not really sure yet. Risks I think one of the reasons why this business is still cheap is that it’s a little hard to understand the business at first. But additionally, the MVNE is reliant on 2 main customers currently, which is quite concentrated. However, the switching costs are high as MVNOs require significant Capex to connect with MVNEs to begin with and there is very little incentive to switch if you’re already connected. (Unless they shut the operations down completely). Additionally, the ‘procurement’ component i.e. rates MEEQ has to pay Mobile Network Operators, are regulated by the government. Whilst the overall move has been for the government to lower rates, which has been good for MEEQ’s COGS, if this changes, it can compress gross margins. The risk doesn’t seem high but it’s worth being careful, especially when much of this cost is out of the company’s control. 2. New Cosmos ElectricNew Cosmos Electric (NCE) is a leading manufacturer of Household Gas detectors. It’s portable detectors are now recognized globally with a real opportunity to expand into the US - where several states are working to mandate Gas detectors in residential homes. With this backdrop, they already have Consolidated Edison $ED as a customer and have a distribution partnership with Lowe’s $LOW . They are also expected to win Home Depot $HD as another partner. This currently trades at 1.0x book. New Cosmos Electric is a leading provider of Gas Detection Systems. The range of products cover both for industrial and household use. In fact, NCE was the world’s first inventor of Gas Sensors for household applications and consequently has a high share in the Japanese market, with close to 45% for household applications and 30% for industrial. (Riken Keiki [Ticker:7734] is the no.1 player here, also interesting co).
One of their main strengths is their long experience and R&D capabilities, which leads to product competitiveness. Most recently, they’ve developed a MEMS Methane Gas Sensor which is garnering attention in the US due to the high energy efficiency and portability. A big opportunity for the business is their expansion in the US, which I think they have better odds of achieving than the average Japanese company. This makes the TAM much larger than Japan and (I believe) deserves a premium. The company has long established a partnership with Energy giant Con Edison (Ticker: $ED ) to install their detectors. Con Ed first became a customer of NCE after their Gas Explosion incident in 2014 promting to ensure that no such failure occurred again. Since, the company uses the sensors across it’s gas distribution infrastructure close to households. This has provided NCE with credibility in the US market. Furthermore, several districts in the US are now moving to legally mandate the installation of Gas Detectors in households. Although the timeline is not clear for many states and some states may take years. Nonetheless, this could be a huge opportunity for NCE. The most immediate is in New York City where the deadline was May 2025 but extended to '“no sooner than Jan 1 2027.” - based on NYC Local Law 157 It’s rare to see Lowe’s being mentioned for a Japanese stock but they are already selling NCE products. Home Depot is also set to start this year. Given that the ASP in the US is higher, there are large implications on the group margins if they manage to scale this successfully. Another tailwind for NCE is that the company is looking to improve shareholder payouts. This has been a historically cash-rich company that did not have sufficient shareholder friendliness. But this seems to be changing as they announced their first (small) buyback as well as a dividend payout ratio. Risks Key risk factors here are that Chinese players are apparently trying to enter the US this year with lower-quality but cheaper products. Whilst quality is so important for a use case so critical, consumers may not think that way. Competition could likely increase this year and nonetheless, this will be a good ‘test’ for NCE’s competitiveness. Furthermore, there has been an extension of the deadline in New York City given the insufficient supply of detectors. The company also expects this extension to slow down the strong revenue growth they’ve recently seen in the US as a result. Nonetheless, they are operating at close to full capacity and are working to expand their production capacity. Furthermore, their MEMS detector is battery-powered and this could potentially lead to further competitiveness for NCE. New York City is also requiring that they need at least 4 suppliers that can provide sensors by the January 2027 deadline, before the law can be in place which is basically an open invitation for competition so this needs to be watched closely. Overall, the general trend seems to be the need for more sensors in the US but the timeline as to when and how this will hit NCE P&L is unclear. One other thing I don’t like as a consumer good is that there isn’t a recurring component for this business i.e. there are no ‘maintenance’ revenues as industrial sensors might have. So there are short-term risks to the story, but I’m watching it closely. ... Subscribe to Made In Japan to unlock the rest.Become a paying subscriber of Made In Japan to get access to this post and other subscriber-only content. A subscription gets you:
|
Wednesday, January 14, 2026
Japan Idea Radar #3




Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment