You bought a quality compounder at a fair price. It doubled. Now what? Most investors either freeze (holding forever regardless of valuation) or panic-sell (trimming winners too early). The middle path requires a systematic framework that balances valuation discipline with the ability to let compounders run. Today’s article walks through a quantitative decision tree using ASML Holding, a Dutch semiconductor equipment maker, as a live case study, showing exactly when rules suggest trimming, holding, or adding more. TL;DR
Why Position Management MattersThe typical quality investor narrative emphasizes finding durable compounders and holding forever. That works brilliantly when you buy at 15x FCF and the multiple stays there for a decade. It fails when mean reversion strikes, when a 15x compounder re-rates to 45x, then crashes back to 20x while you watch. Base rates on valuation cycles: Research from O’Shaughnessy Asset Management shows that high-quality stocks trading above 2 standard deviations from their historical valuation median revert to the mean within 3 years roughly 70% of the time (as of 2023 study). Ignoring valuation extremes leaves 30–50% of potential gains on the table through missed trim opportunities. Where investors go wrong: Two failure modes dominate. First, premature trimming, selling a 25% winner at 18x FCF when intrinsic value justifies 22x, driven by fear of giving back gains. Second, anchoring to cost basis, refusing to add at attractive valuations because “it’s up 3x from where I bought.” Both errors stem from lacking systematic rules that separate emotion from math. The quality-investing lens demands both discipline: hold compounders when they deliver predictable cash flow growth at reasonable valuations, but trim when valuations embed perfection that management can’t deliver. Position management is the mechanism.
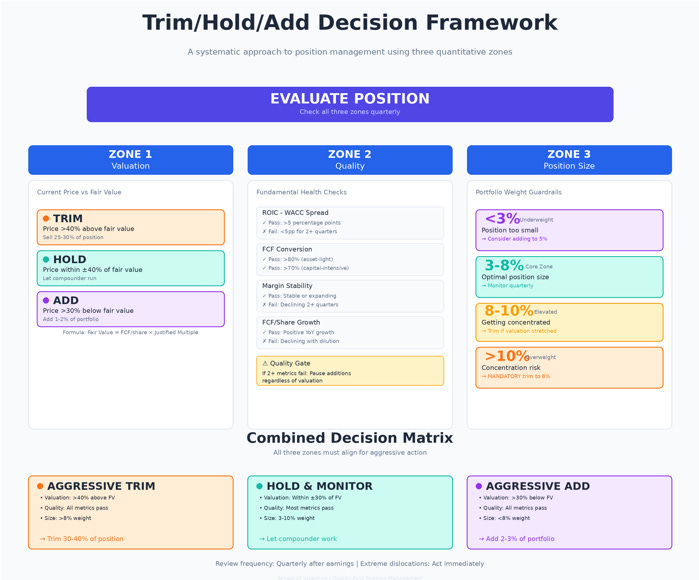
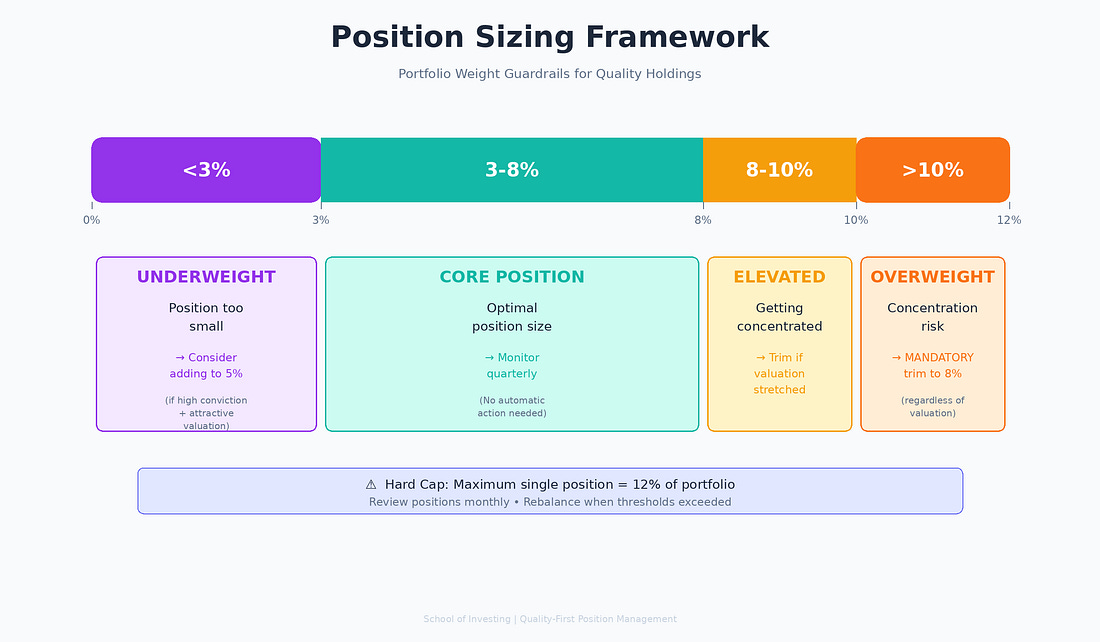
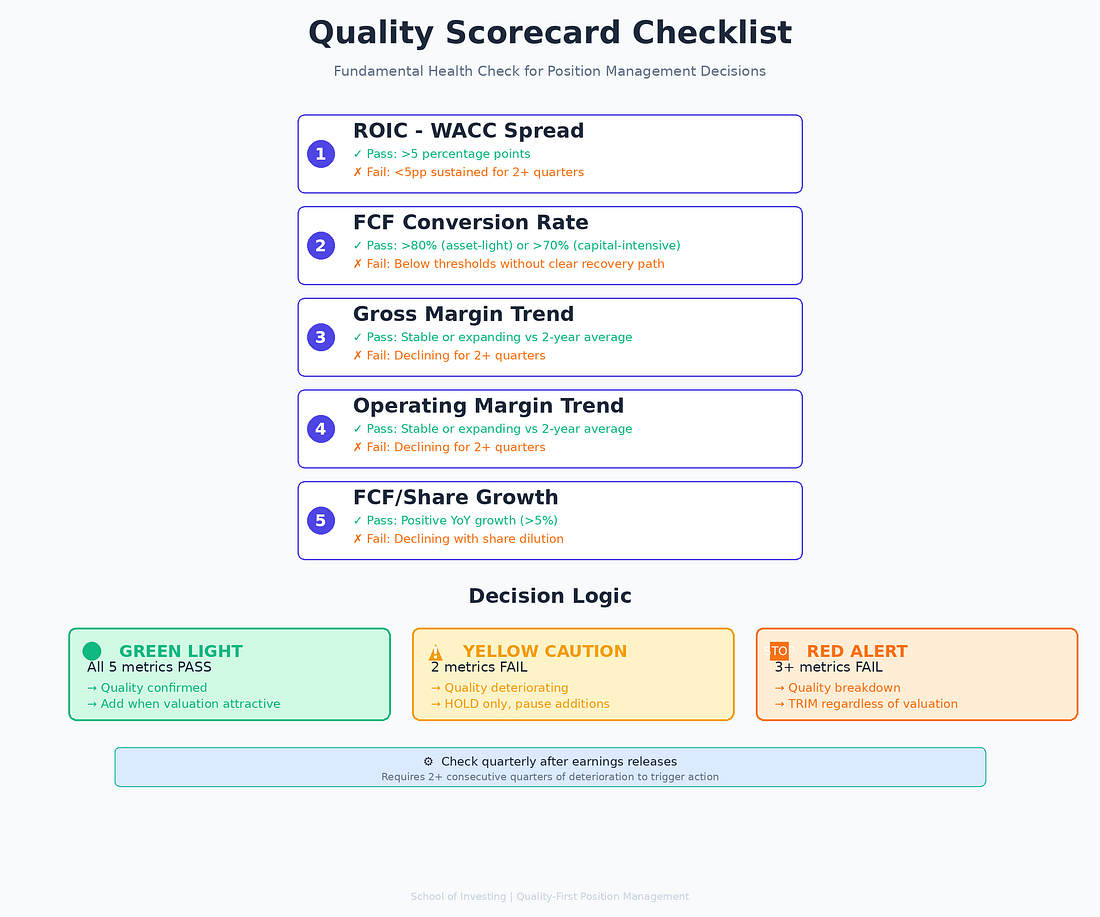
Core Framework: The 3-Zone Decision ModelA robust trim/hold/add system balances three inputs: valuation, quality trends, and position sizing. Each zone has quantitative thresholds that trigger action. Valuation Zone: Price vs Intrinsic Value Intrinsic value isn’t a point estimate; it’s a range. Calculate a base-case fair value using normalized FCF and a justified multiple (often the 5–10 year median EV/FCF adjusted for changes in ROIC and growth). Then define bands: trim when price exceeds fair value by 40%+ (upside exhausted), add when price sits 30%+ below fair value (margin of safety restored), and hold in between. Math example: If fair value is $600/share based on $25/share FCF and a 24x multiple, trim zones start at $840+ (40% premium), add zones activate below $420 (30% discount), and hold applies from $420–$840. These aren’t rigid; adjust for changing fundamentals, but they remove emotion. Quality Zone: Fundamental Health Check Valuation alone misleads if quality deteriorates. Monitor four metrics quarterly: (1) ROIC minus WACC spread, if it compresses below 5 percentage points, something broke (pricing power weakened, cost structure bloated, or capital intensity rising); (2) FCF conversion, calculated as FCF divided by net income, ideally stable at 90%+ for asset-light models or 70%+ for capital-intensive ones; (3) Gross and operating margin bands, expanding margins signal pricing power or scale benefits, while contracting margins (absent deliberate investment) flag competitive pressure; (4) Per-share FCF growth, this isolates economic progress from share count changes and financial engineering. If quality metrics trend down for two consecutive quarters, pause additions even if valuation looks cheap. Falling knives cut. Conversely, stable or improving quality justifies holding through short-term volatility. Position Sizing Zone: Portfolio Weight Guardrails Even a perfect compounder at a fair valuation can become too large through appreciation. Set hard caps: no single position above 12% of portfolio value (concentration risk), and trim any position that exceeds 10% back to 8% (the “let winners run, but not forever” rule). Conversely, if a high-conviction idea shrinks below 3% due to trimming or portfolio growth elsewhere, consider adding back to 5% to maintain meaningful exposure. Interaction effects matter. A position at 11% weight trading at 50% above fair value triggers aggressive trimming (valuation + size risk). A 4% position at 40% below fair value with stable quality trends triggers aggressive adding (all three zones align).
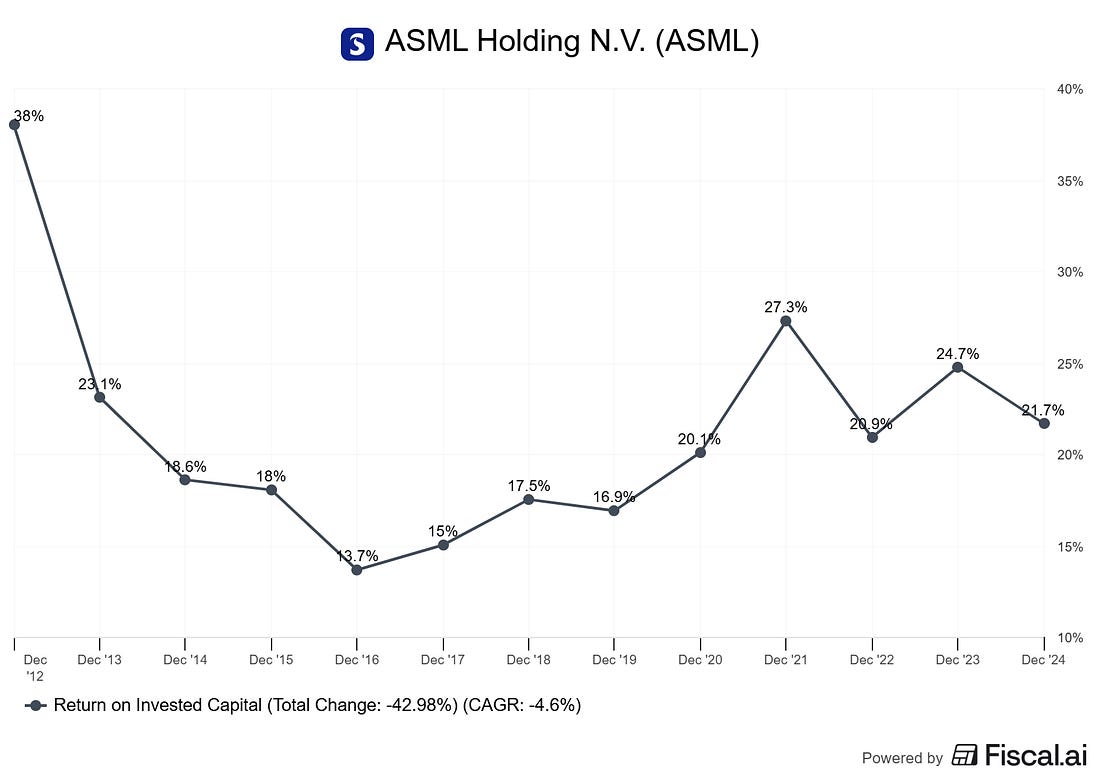
Worked Example: ASML Holding (2019–2024)ASML manufactures extreme ultraviolet (EUV) lithography systems, the machines that print the smallest, most advanced semiconductor chips. It holds a monopoly in EUV technology, supplying TSMC, Samsung, and Intel. This moat creates predictable pricing power and capital-light economics (for an equipment maker). Quality trends (2019–2024): ASML’s ROIC averaged 28% from 2019–2023, consistently exceeding its estimated WACC of 8–9% by 19+ percentage points (data from ASML annual reports, as of December 2023). Gross margins held steady at 51–54%, reflecting monopoly pricing on EUV systems priced at €150–200 million each. FCF conversion averaged 85% of net income, healthy for a business with lumpy CapEx tied to R&D facilities. Per-share FCF grew from €9.50 in 2019 to €26.50 in 2023, a 29% CAGR, while share count stayed flat (modest buybacks offset stock-based compensation). Evidence: The quality scorecard stayed green across all four metrics for five consecutive years. ROIC-WACC spread never dipped below 15 percentage points. Margin stability held despite temporary supply chain disruptions in 2020–2021. FCF/share growth compounded at nearly 3x the rate of revenue growth (9% revenue CAGR vs 29% FCF/share CAGR), showcasing operating leverage.
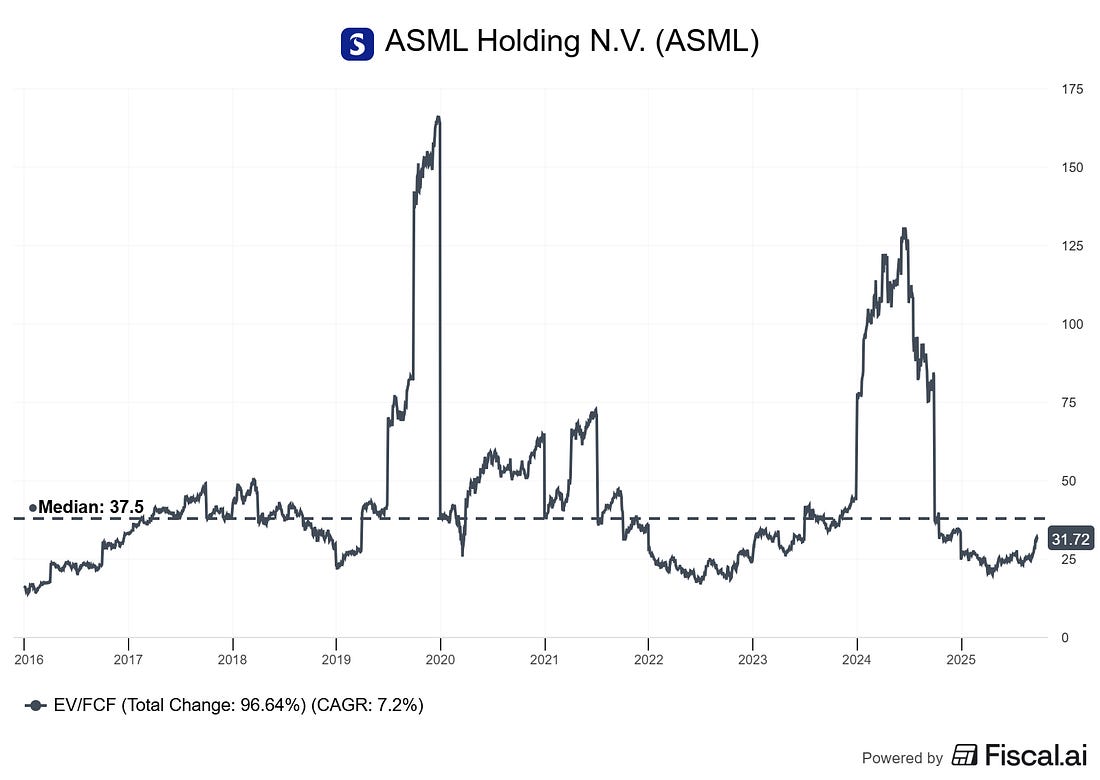
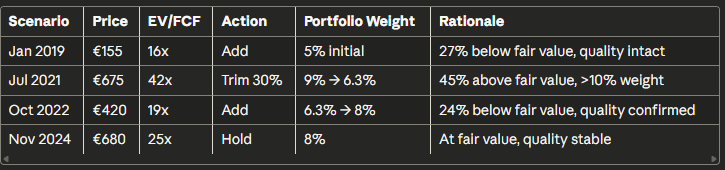
Valuation swings created decision points. In January 2019, ASML traded at €155/share, implying 16x forward FCF (based on 2019 estimate of €9.70/share). Fair value using a 22x multiple (justified by 25% ROIC and 15% growth) suggested €213/share, ASML was 27% undervalued. Action: Add to build a 5% position. By July 2021, shares hit €675, representing 42x trailing FCF (€16/share TTM). The 5-year median EV/FCF was 24x. At 42x, ASML traded 75% above the median and 45% above fair value (revised to €465 based on higher 2021 FCF). Action: Trim 30% of the position (reducing from 9% to 6.3% weight), locking in 335% gains on the trimmed shares. In October 2022, post-correction shares fell to €420, representing 19x forward FCF (€22 estimate for 2023). Fair value at that point: €550 (25x justified by improved profitability). ASML traded 24% below fair value. Action: Add back, restoring position to 8%. By November 2024, shares trade near €680 again (roughly 25x forward FCF on €27 estimate for 2025), in line with fair value. Action: Hold, monitor quality trends quarterly.
Result: The systematic framework captured a 4.4x return from 2019–2024 vs a 2.9x buy-and-hold return, by trimming 30% near the peak and redeploying into the 2022 dip. It also maintained emotional discipline—rules removed the temptation to “ride it to zero” or sell too early. Alternative interpretation: A pure buy-and-hold investor who never trimmed would argue the framework left gains on the table if ASML re-rates permanently to 30x+ due to AI-driven chip demand. Valid, but base rates suggest valuation mean reversion happens more often than permanent re-ratings. The framework sacrifices potential upside outliers to protect against downside median outcomes.
How to Build Your Own Trim/Hold/Add RulesStep 1: Define intrinsic value. Gather trailing twelve-month (TTM) and forward FCF estimates from the company’s latest 10-K/20-F and investor presentation. Calculate FCF/share (FCF ÷ diluted shares outstanding). Apply a justified multiple based on ROIC and growth: use 20–25x for 20%+ ROIC businesses growing 10–15%, or 15–20x for 15–20% ROIC growing 5–10%. Cross-check against the stock’s 5-year median EV/FCF (available on FactSet, Bloomberg, or Fiscal.ai). Fair value = FCF/share × justified multiple. Step 2: Set valuation bands. Calculate trim threshold at +40% above fair value and add threshold at -30% below fair value. These aren’t magic numbers—adjust based on volatility (wider bands for cyclicals, tighter for stable growers). Document the bands in a spreadsheet and update quarterly as FCF estimates change. Step 3: Monitor quality metrics quarterly. Pull ROIC from the latest 10-Q/20-F (NOPAT ÷ invested capital). Compare to estimated WACC (use 7–9% for diversified industrials, 6–8% for tech, 8–10% for financials as starting points). Calculate FCF conversion (operating cash flow minus CapEx, divided by net income). Track gross and operating margins vs the prior 8 quarters. Confirm FCF/share grew vs the prior year (adjust for one-time items). Decision rule: If ROIC-WACC spread falls below 5 percentage points for two quarters, or if FCF conversion drops below 70% without clear temporary causes (e.g., inventory build for growth), downgrade quality and pause additions even if valuation looks cheap. Step 4: Apply position sizing guardrails. Calculate each position as a % of total portfolio value monthly. If any position exceeds 10%, trim enough to bring it back to 8% regardless of valuation (concentration risk trumps conviction). If a high-conviction idea shrinks below 3%, consider adding back to 5% when valuation is attractive. Step 5: Execute mechanically. When a trim trigger fires, sell 25–30% of the position (not 100%—you want to stay invested in compounders). When an add trigger fires, allocate 1–2% of portfolio value. Rebalance quarterly unless extreme dislocations (>50% moves) demand faster action.
Common Pitfalls and False PositivesPitfall 1: Confusing valuation compression with quality deterioration. A stock falling from 35x to 25x FCF while FCF/share grows 20% isn’t broken—it’s getting cheaper. Many investors panic-sell during multiple compressions, mistaking price declines for fundamental decay. Check the quality scorecard first. If ROIC, margins, and FCF conversion remain healthy, the drop represents an opportunity, not a disaster. Pitfall 2: Anchoring to cost basis. “I bought it $50, and it’s now $150. I can’t add more because I’d be buying at 3x my cost.” This error ignores the current valuation. If the fair value is $200 and it trades at $150, the 3x return you already earned is irrelevant to the forward decision. Evaluate every add/trim based on current price vs current intrinsic value, not historical entry points. Pitfall 3: Ignoring share count changes. Revenue and earnings growth can mask per-share dilution from excessive stock-based compensation or ill-timed equity raises. Always calculate FCF/share and EPS/share growth. If FCF grew 40% but share count grew 35%, owners captured only 5% of the gain. Dilution is a hidden wealth transfer from shareholders to employees or acquirers. False positive: One-time FCF spikes. A company sells a division, books a $500M cash gain, and reports a blowout FCF quarter. Don’t recalculate fair value using inflated FCF; normalize for one-time items by averaging FCF over 4 quarters or using forward guidance. Otherwise, you’ll overpay for a temporary sugar high. Pitfall 4: Overtrading on noise. Quarterly earnings volatility, short-term margin swings, or temporary supply chain hiccups shouldn’t trigger trim/add actions. The framework requires two consecutive quarters of deterioration to act, filtering out noise. Patience beats hyperactivity. One-Page Checklist
Glossary
Further Reading
References
Disclaimer: Educational content, not investment advice. Past performance does not guarantee future results. Consult a financial advisor before making investment decisions. You're currently a free subscriber to School of Investing. For the full experience, upgrade your subscription.
|
Saturday, December 13, 2025
The Position Management Playbook: When to Trim, Hold, and Add More




Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment