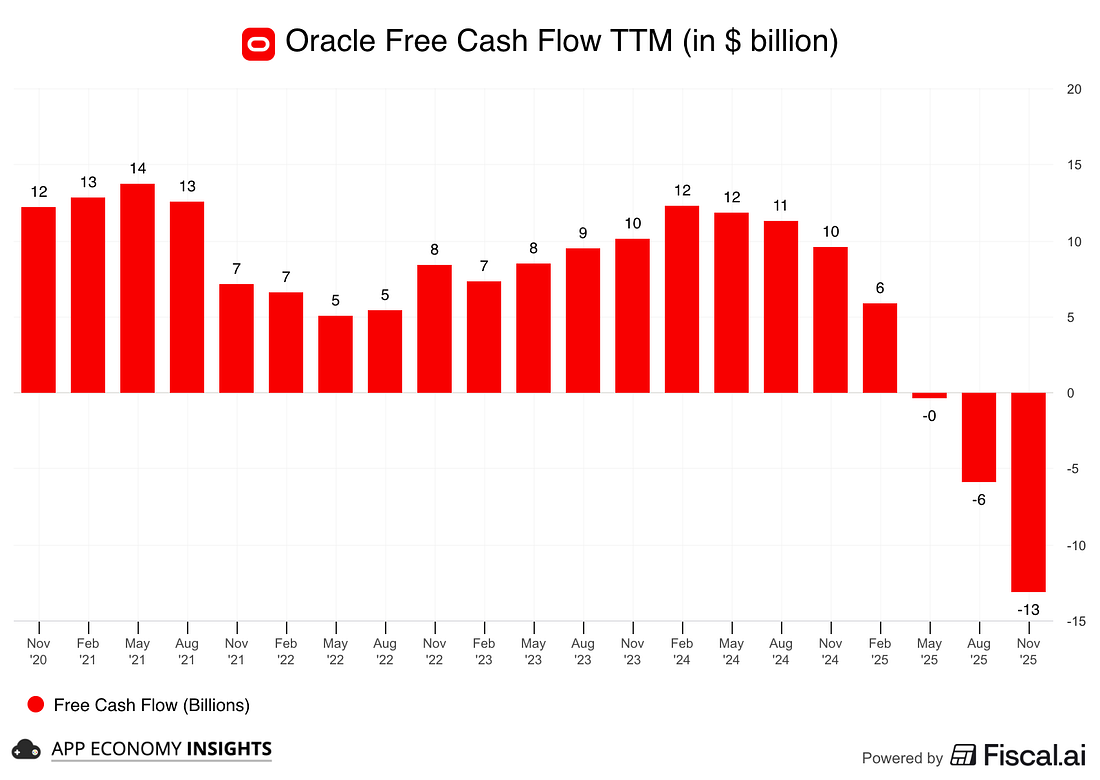
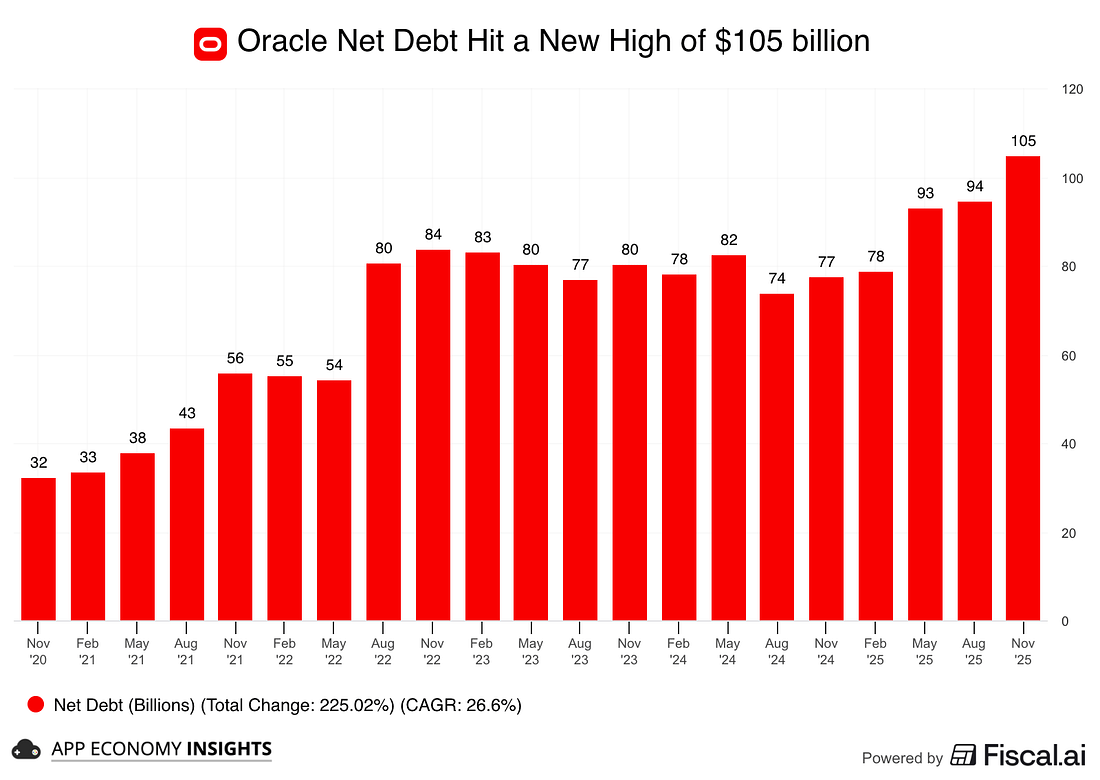
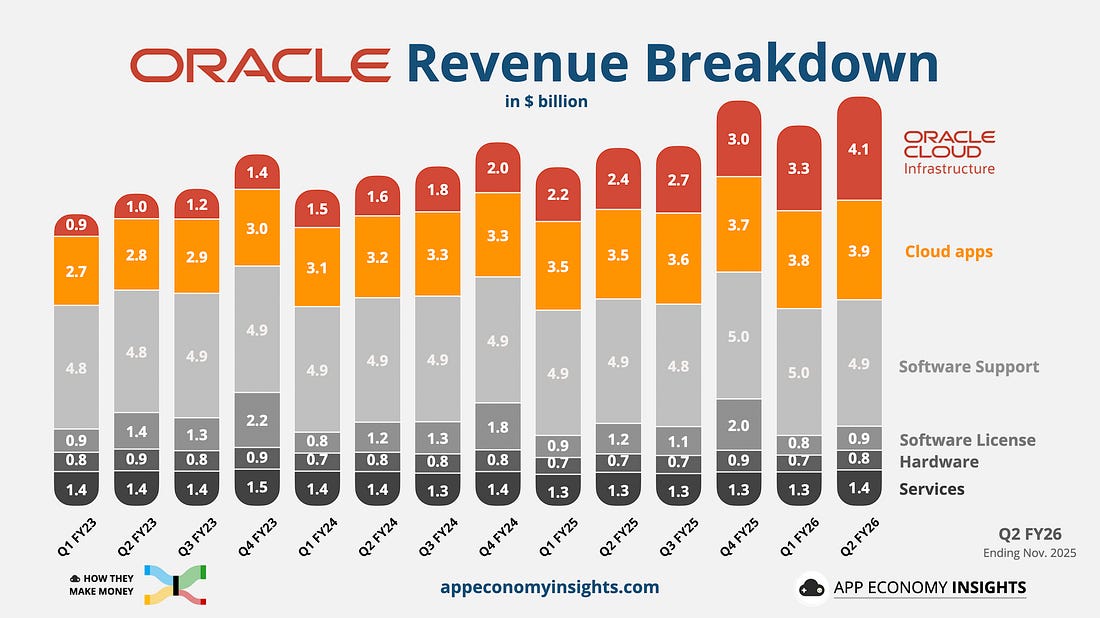
Welcome to the Free edition of How They Make Money. Over 250,000 subscribers turn to us for business and investment insights. In case you missed it: Oracle is bleeding cash and must prove it can executeDespite another jaw-dropping surge in future contracts, Oracle shares slumped 11% following its quarterly report. With this latest drop, shares are now over 40% below their September peak. Why? The company is betting the farm on building the AI infrastructure of the future. The backlog is surging, but so is the bill to build it. Oracle just raised its FY26 CapEx forecast by $15 billion to $50 billion, fueling fears about debt and cash burn. Free cash flow declined to negative $13 billion over the past 12 months (negative $10 billion in the last quarter alone).
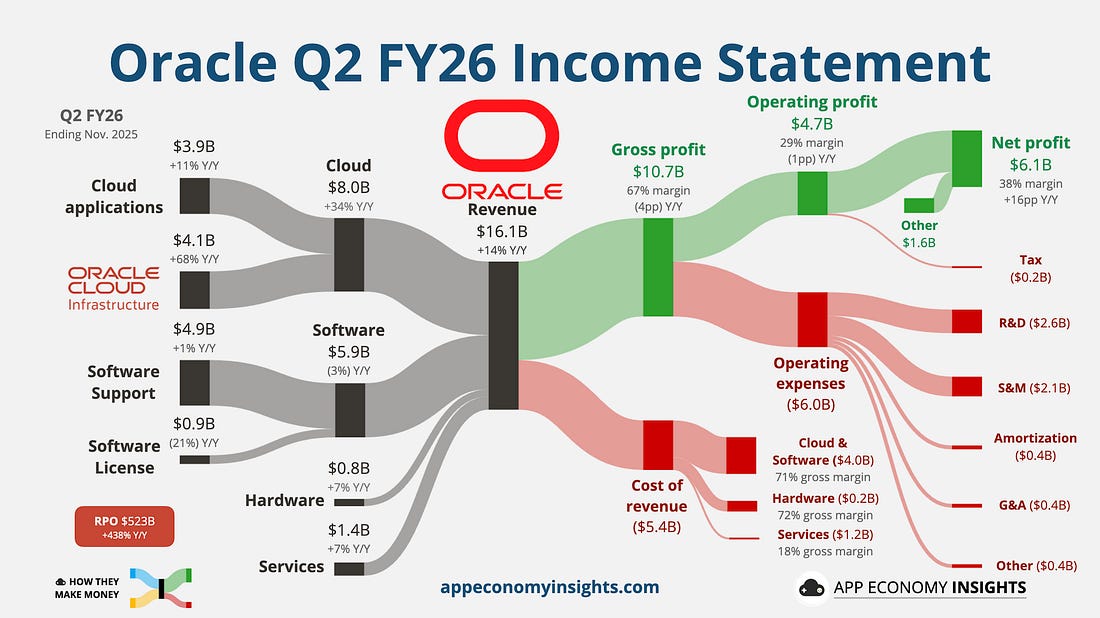
Meanwhile, actual revenue missed estimates slightly, reminding investors that signing a contract is easier than powering up a data center. Let’s review the numbers behind the sell-off and the continued AI hypergrowth. Today at a glance:
1. Oracle has something to proveQ2 FY26 key metrics:
Income statement:
Cash flow:
Balance sheet:
So what to make of all this?
What to watch moving forward
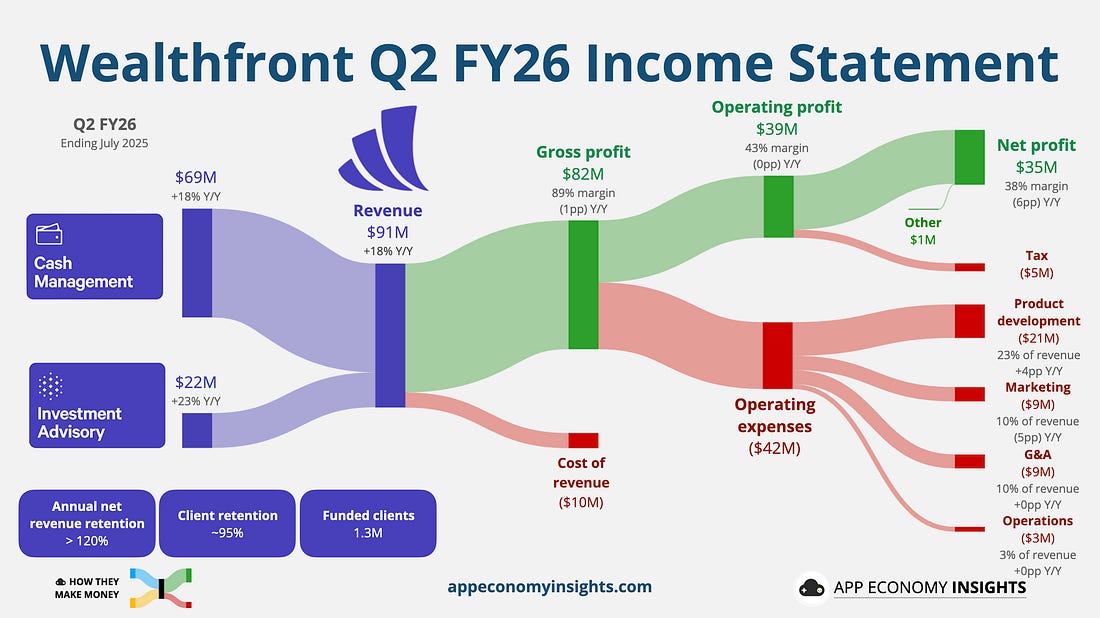
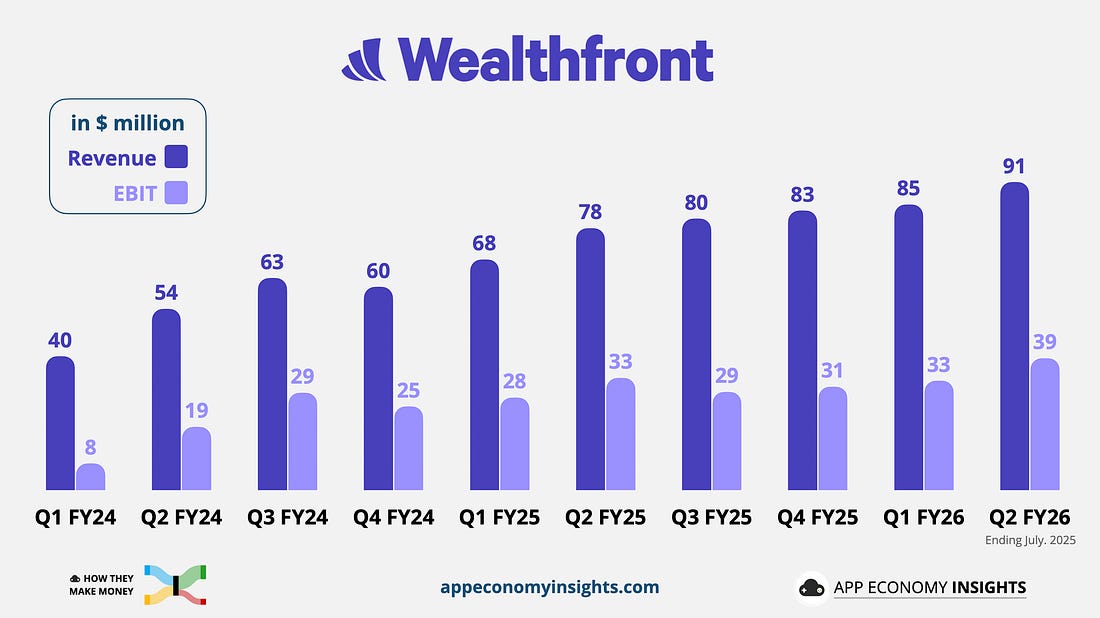
📊 Want to see how AMD and NVIDIA recently performed? Check out our latest monthly Earnings Visuals report. 🤖 Robo-Advisor Wealthfront Goes PublicThree years ago, Wealthfront was supposed to disappear. The original robo-advisor had agreed to be acquired by UBS for $1.4 billion, acknowledging that the path to independence was too steep. But after the deal collapsed in 2022, Wealthfront pivoted. Today, the company is going public with an IPO targeting a $2 billion valuation under the ticker WLTH. By walking away from the acquisition and betting on itself, the company has effectively created ~$600 million in shareholder value during a brutal fintech winter. For years, Wealthfront was known as the pioneer of automated investing, collecting a modest 0.25% fee to manage your ETF portfolio. But if you look under the hood of their S-1, you’ll find a very different business model driving the returns today. How did they pull it off? They stopped being just an investment manager and started acting like a bank. 📊 How Wealthfront Makes MoneyThe narrative used to be about “assets under management” (AUM) and advisory fees. While those are still growing, they are no longer the main event. In the most recent quarter (Q2 FY26, ending July 2025), Wealthfront reported $91 million in net revenue. Here is the breakdown that matters:
The takeaway? Wealthfront makes three times more money from the cash sitting in your high-yield account than it does from managing your investments. This shift occurred when they launched their cash account, leveraging partner banks to offer high yields. By capturing the spread (the difference between what they earn on client cash and what they pay out in interest), they unlocked a massive, high-margin revenue stream. 📈 The Bull Case: A Profitable FintechUnlike the wave of cash-burning fintech IPOs we saw in 2020 and 2021, Wealthfront is structurally profitable.
📉 The Bear Case: The Interest Rate TrapThe very thing that makes Wealthfront a cash cow today is also its biggest risk. In 2022, Wealthfront was a slowing advisory business (growing just 16% Y/Y according to private market research from Sacra). The pivot to cash management, capitalizing on high interest rates, is behind the acceleration. But this profitability is tied directly to the Federal Reserve. When rates are high, Wealthfront earns a fat spread on $47 billion in cash assets. If the Fed cuts rates significantly, that revenue stream shrinks automatically. Investors buying WLTH are effectively betting that the company can cross-sell these cash-parking clients into fee-paying investment accounts before high yields disappear.
That's it for today. Happy investing! Want to sponsor this newsletter? Get in touch here.Thanks to Fiscal.ai for being our official data partner. Create your own charts and pull key metrics from 50,000+ companies directly on Fiscal.ai. Save 15% with this link. Disclosure: I own AMD, AMZN, GOOG, META, and NVDA in App Economy Portfolio. I share my ratings (BUY, SELL, or HOLD) with App Economy Portfolio members. Author's Note (Bertrand here 👋🏼): The views and opinions expressed in this newsletter are solely my own and should not be considered financial advice or any other organization's views. I would love to hear your feedback! Reply to this email to reach out to me with questions or suggestions. If you enjoyed today's newsletter, please share it with your friends and family! You’ll earn rewards if they subscribe. You’re a free subscriber to How They Make Money. For the full experience, become a Premium subscriber.
|
Friday, December 12, 2025
☁️ Oracle is Bleeding Cash






Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment