Welcome to the Premium edition of How They Make Money. Over 250,000 subscribers turn to us for business and investment insights.
In case you missed it:
Netflix has entered a definitive agreement to acquire the studio and streaming assets of Warner Bros. Discovery for an enterprise value of $83 billion. The deal covers massive intellectual property. But more importantly, the acquisition transforms Netflix from primarily a streaming-only company into a true entertainment conglomerate, expanding its risk profile and strategic direction. But it is far from a done deal. An FTC review is inevitable. President Trump has already weighed in, stating the acquisition “could be a problem.” Adding to the chaos, Paramount just launched a hostile takeover. In a world where Microsoft can buy Activision Blizzard, the vertical nature of the Netflix-Warner merger could be a critical edge. Remember, HBO Max captures only ~1% of US TV time, making it the 9th largest streamer on TV, according to Nielsen. But it brings theatrical distribution and licensing muscles in which Netflix historically plays a small part. Warner Bros. is actively for sale. Regulators may have a hard time arguing that a Netflix acquisition is worse for the industry than a Paramount or Comcast deal. In fact, those would be horizontal mergers between direct competitors (studio and networks), arguably more problematic. Let’s unpack the deal, the drama, and the data. Today at a glance:
FROM OUR PARTNERS
You’re not “rich enough” to waste $40,000 a year on feesMost firms quietly take 1–2% AUM forever. On a $2 million portfolio, that’s $20k–$40k+ gone every single year — enough to fund a luxury car, a dream vacation, or an extra decade of retirement. Range doesn’t play that game. No AUM fees. Just one flat, transparent annual membership fee for unlimited access to a team of human financial advisors + 24/7 access to RAI, your AI wealth advisor. You get institutional-grade tools once reserved for billionaires: direct indexing, real-time tax-loss harvesting, daily rebalancing, and a single dashboard that unites your crypto, real estate, RSUs, and 401(k)s. Built exclusively for high-earning households. Your money compounds. Legacy fees don’t. Disclosure: Not investment advice. Brokerage fees, transaction charges, and other applicable platform fees imposed by our custodian are not included in your membership and will be passed through to you as the Member. Visit www.range.com for details.
1. What Netflix is buyingThe deal involves two steps for current Warner Bros. Discovery (WBD) shareholders expected in the next 12 to 18 months. Step 1: The spin-offBefore the Netflix acquisition closes, WBD will spin off its linear networks business into a new, publicly traded independent company dubbed Discovery Global.
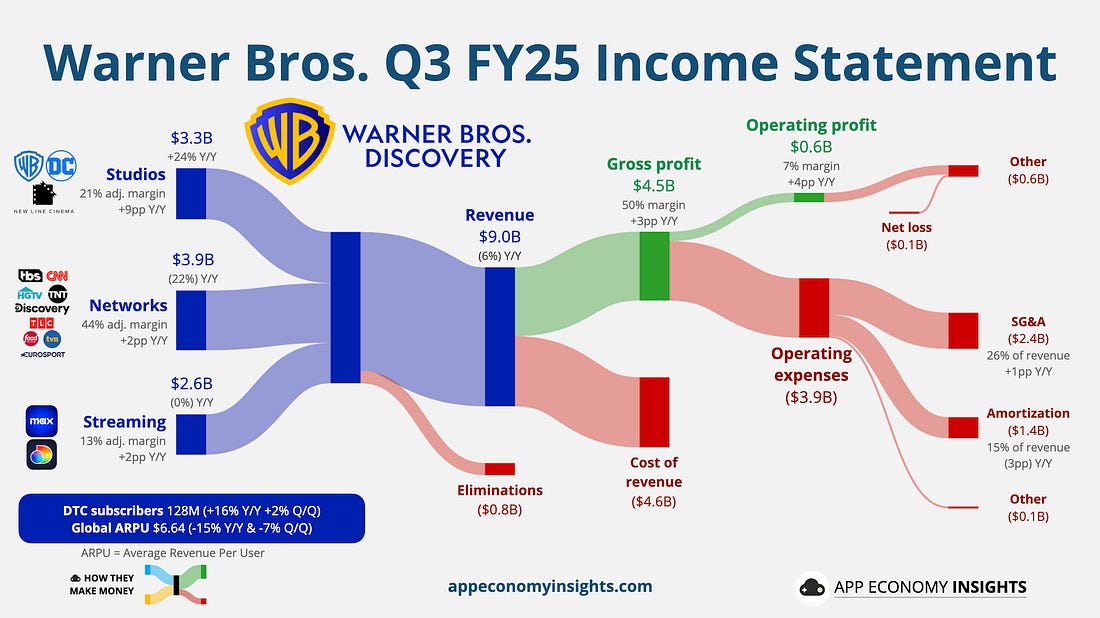
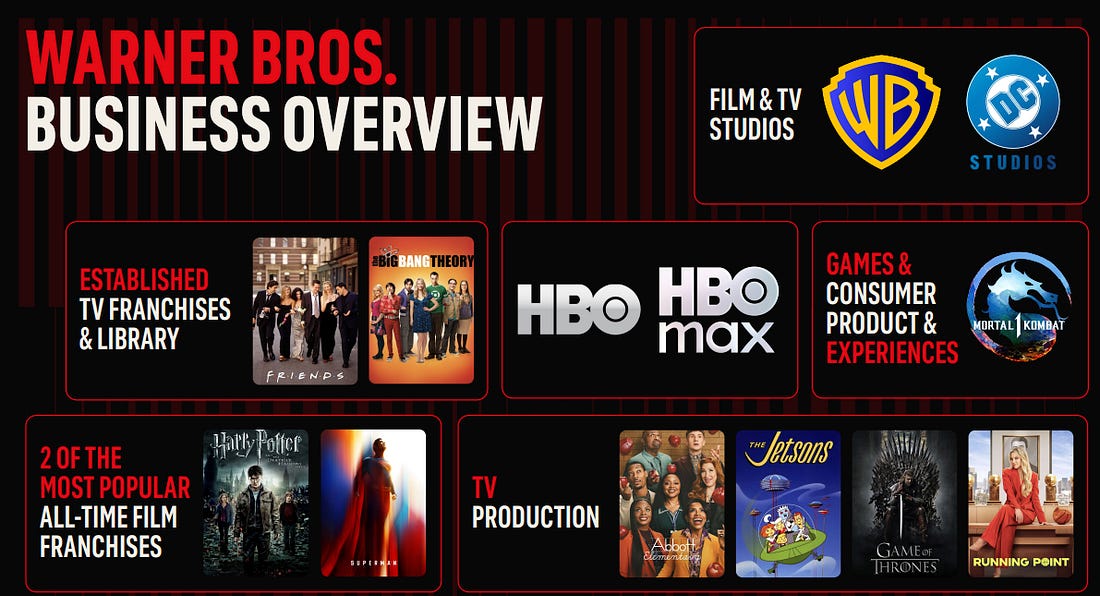
Step 2: Netflix acquires the restNetflix will acquire the remaining entity:
In short, Netflix buys the IP engine without inheriting the dying cable bundle.
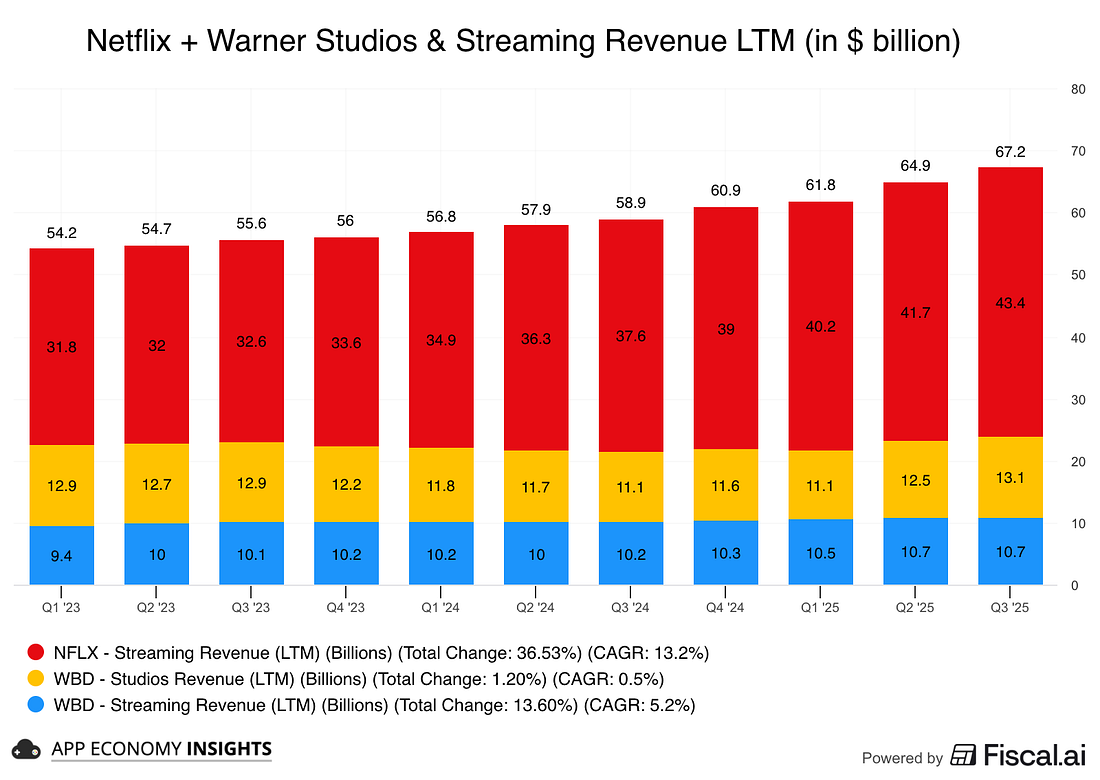
Here’s how the combined revenue would look:
That puts the combined entity at ~$67 billion of annual revenue. Just barely ahead of YouTube, which has an estimated ~$60 billion annual run rate (ads + subscription).
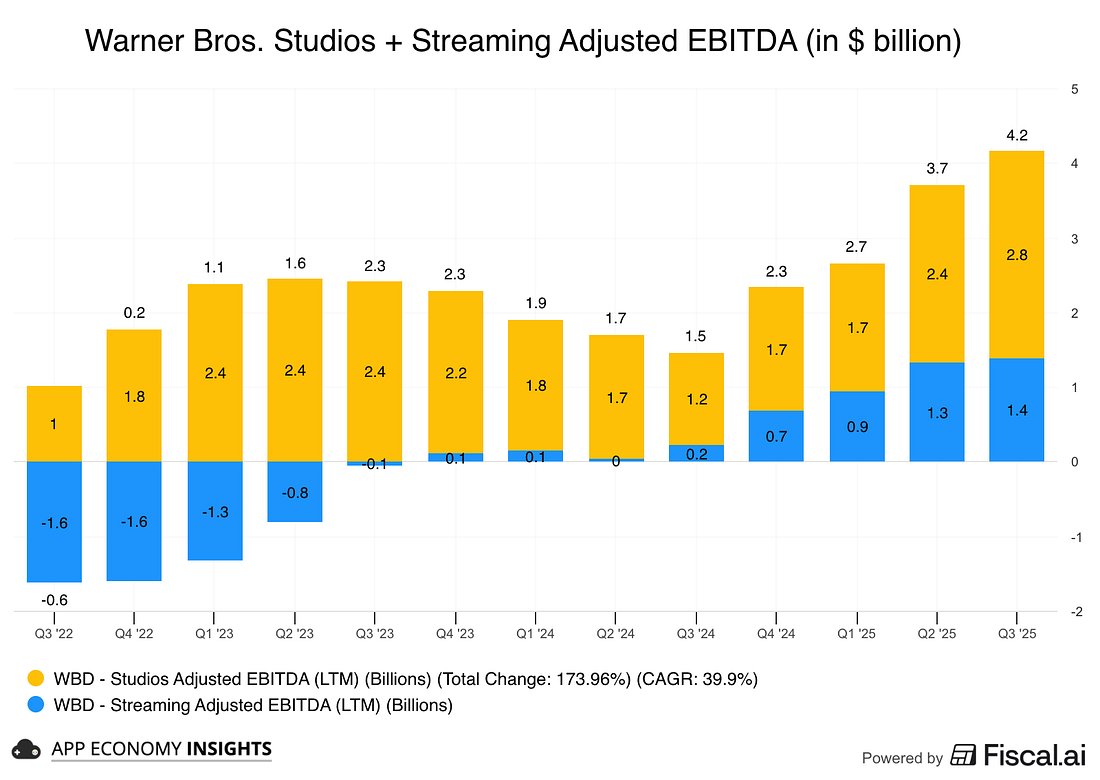
Turning to profitability, Warner’s Studios and Streaming segments achieved $4.2 billion in adjusted EBITDA in the past 12 months. Most noteworthy is the progress made in the Streaming segment as more cord-cutters switch to HBO Max (128 million subscribers globally in Q3). But the Studios segment can be hit or miss and depends on big new releases.
ValuationAt an enterprise value of ~$83 billion, Netflix is essentially paying ~20x EBITDA. It gets to 25x if we use Warner’s expected EBITDA of $3.3 billion for FY26. That’s a big premium for a no-growth business, as you would expect after a bidding war. For perspective, Disney is currently trading at ~12x EBITDA. Critically, Netflix expects $2-to-3 billion in annual cost savings by year 3. If they can deliver on the high end of this goal, the valuation comes down to ~12x EBITDA and makes more sense. In addition, there is a wide range of value that could be unlocked and not reflected in trailing financial metrics:
A massive break-up feeNetflix agreed to a massive $5.8 billion termination fee.
Meanwhile, if WBD shareholders vote down the deal or Warner takes a rival offer, there is a $2.8 billion reverse breakup fee. If Paramount makes another bid, it would be on the hook for that fee, making it less likely. 2. Netflix embraces leverage...Subscribe to How They Make Money to unlock the rest.Become a paying subscriber of How They Make Money to get access to this post and other subscriber-only content. A subscription gets you:
|
Tuesday, December 9, 2025
🍿 Netflix + Warner Bros. Breakdown







Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment