Recurring revenue businesses, particularly dominant software platforms like Adobe and Autodesk, command a significant premium in public markets. As investors, it’s not enough to pay the multiple; we must understand the fundamental drivers that justify that high price and, crucially, know where those assumptions break. Today’s article will teach you how to translate core quality metrics—like Return on Invested Capital (ROIC) and Free Cash Flow (FCF) conversion—into a rigorous valuation framework, specifically using a reverse Discounted Cash Flow (DCF), to stress-test market expectations for these two recurring revenue giants. TL;DR
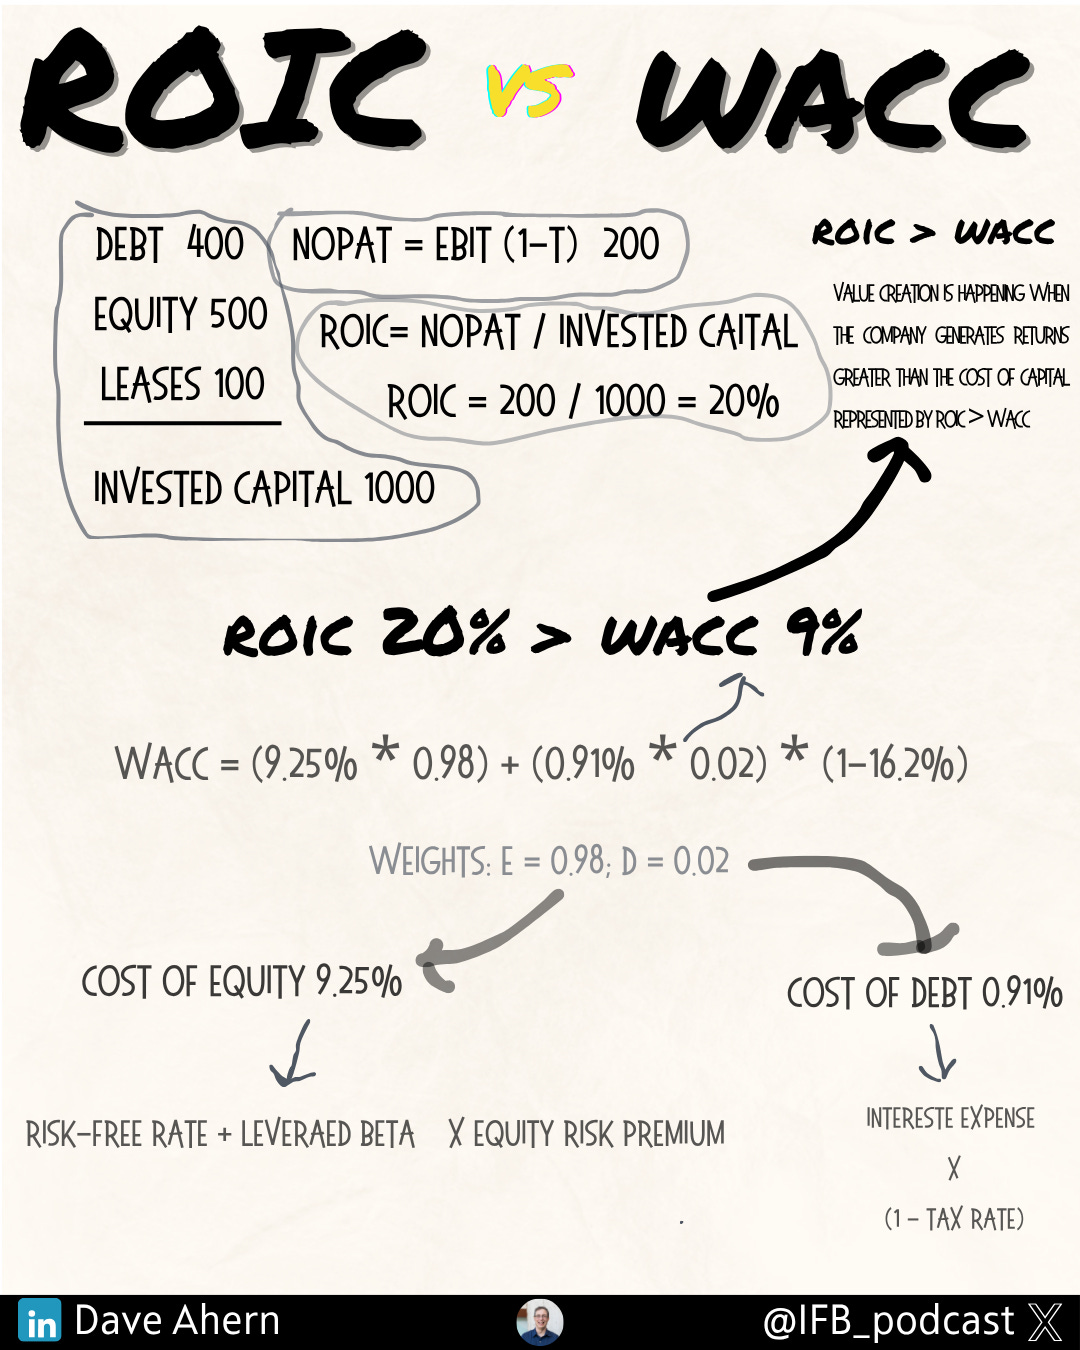
Why It Matters (Context, Base Rates, Where Investors Go Wrong)High-quality businesses with sticky, recurring revenue models are the holy grail for many investors. Companies like Adobe (creative and document software) and Autodesk (design and engineering software) transitioned successfully from selling one-time licenses to a subscription model, creating powerful moats and extremely predictable cash flows. This predictability gives them a much lower business risk profile. The Base Rate Challenge: Investors face the challenge that the market rarely misses this quality. The average S&P 500 company has a typical Enterprise Value (EV) to Free Cash Flow (FCF) multiple of around $15x to $20x. Dominant subscription software companies often trade at $30x, $40x, or even higher. When you pay $40 for one dollar of current FCF, you are making a massive long-term bet on growth and durability. Most companies simply fail to maintain the blistering growth rate embedded in such a high multiple over the requisite decades. Where Investors Go Wrong: Most investors stop at comparing multiples—Adobe is cheaper than X or more expensive than Y. Quality investing demands a deeper look. We need to quantify the exact future performance the market expects. If a stock is priced to deliver 15% revenue growth over 10 years, and you think it can only deliver 12%, the stock is likely an avoid, regardless of its quality. This is where the reverse DCF shines: it forces you to confront the market’s assumptions directly. Core Concepts in Quality ValuationA high valuation is justified only if the company can generate outsized returns on new capital for a long time. The entire recurring revenue valuation premium is built on a few core concepts. ROIC vs WACC and Value CreationReturn on Invested Capital (ROIC) is the most important metric for a quality investor. It measures the profit a company generates per dollar of capital invested in the business. ROIC = Net Operating Profit After Tax (NOPAT) ÷ Invested Capital The quality bar is ROIC > WACC.
Reinvestment Runway and Capital IntensityA high ROIC is great, but it’s useless without the ability to reinvest those profits. Reinvestment Runway refers to the duration and scale of high-return investment opportunities (e.g., R&D, sales expansion, M&A). Capital Intensity refers to the amount of capital required to generate a dollar of revenue or profit. Software companies are generally low-capital-intensity—they don’t need large factories or extensive property, plant, and equipment (PP&E). This enables them to convert a high percentage of accounting profit (Net Income) into tangible cash profit (Free Cash Flow), which is then available for high-ROIC reinvestment or return to shareholders. A high FCF Conversion ratio (FCF ÷ Net Income) is a hallmark of a quality, capital-light business. Unit Economics and Per-Share MetricsFor subscription businesses, unit economics relate to the profitability of an average customer. Key metrics like Net Revenue Retention (NRR)—which measures existing customer spending growth (including upsells and net of churn)—must be sustainably above 100% for high-growth software. Furthermore, a quality investor must always use a per-share framing. Management might report strong Net Income growth, but if they issue excessive Stock-Based Compensation (SBC) without corresponding share repurchases, the per-share growth for existing owners is diluted. You must always track FCF per Share and EPS per Share alongside the raw company-level figures. Moat Durability and Evidence (Not Claims)A moat is a structural competitive advantage that protects a company’s high ROIC from competition. For companies like Adobe and Autodesk, the primary moats are:
Evidence: A quality investor looks not at management claims but at tangible evidence such as consistently high NRR, stable margins (especially Gross Margin), and a sustained ROIC-WACC spread over 10 years. Valuation Frameworks, Drivers, and Scenario Design (Valuation Focus)For a dominant, mature software company with recurring revenue, standard multiples like Price-to-Earnings (P/E) or EV/EBITDA can be misleading due to varying capital structures and non-cash items. FCF is a cleaner measure of true owner earnings. We prefer an Enterprise Value to Free Cash Flow (EV/FCF) multiple for quick comparison, but the real work is in the reverse DCF. The Reverse DCF:
Scenario Design: Quality investors use scenarios to test the durability of growth. Instead of a single point estimate, we design three cases:
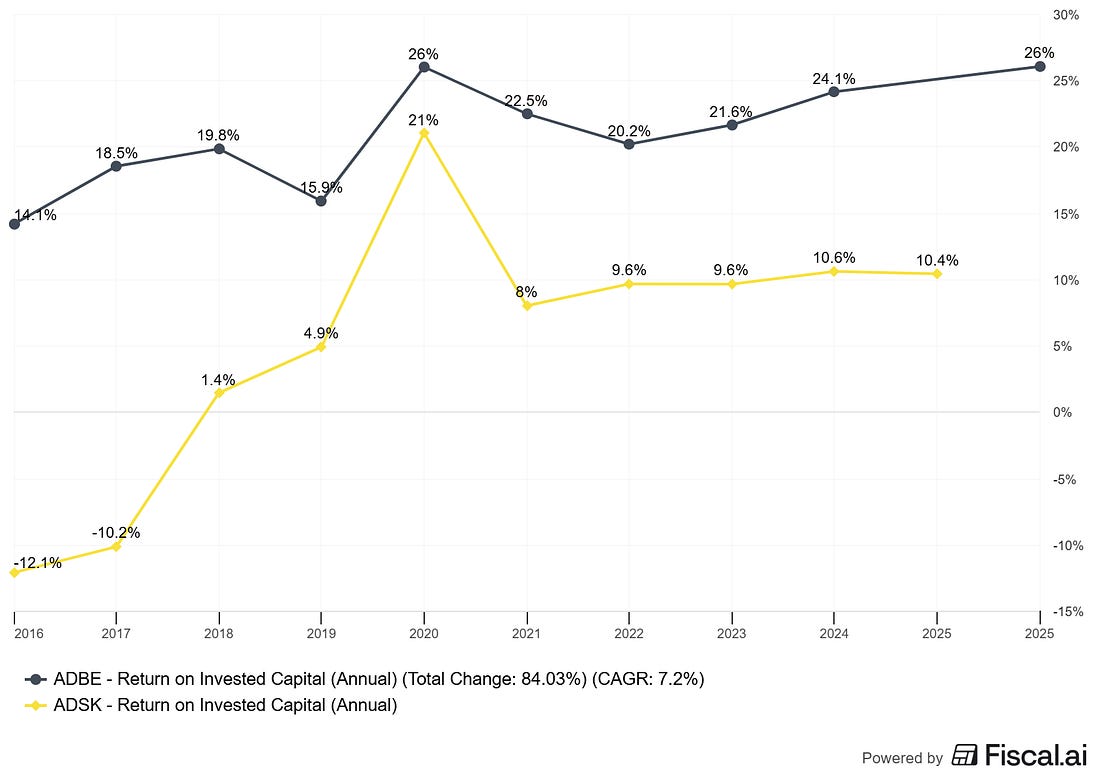
Worked Example: Adobe ($ADBE) and Autodesk ($ADSK)Adobe and Autodesk are both US-based, recurring-revenue software incumbents. Adobe dominates the creative and document markets (Creative Cloud, Document Cloud, Experience Cloud). Autodesk is the standard for computer-aided design, engineering, and construction (AutoCAD, Fusion 360). Both successfully navigated the license-to-subscription transition, making them excellent test cases for a quality valuation. Data Snapshot (FY 2024 Endings - Adobe: Nov 2024, Autodesk: Jan 2024) Data compiled from company 10-K and 8-K filings, Q4 2024 earnings materials, and market data as of October 2025. Evidence: Operating Margin and FCF Conversion Adobe has consistently exhibited higher gross and operating margins, reflecting its dominant, non-substitutable products in the creative suite (Photoshop, Illustrator). Autodesk, while dominant in its own niche, operates in a slightly more fragmented market. FCF Conversion: Autodesk shows an exceptionally high FCF conversion ratio (~ 205% in FY24). This isn’t magic; it is largely due to its significant deferred revenue balance (customer cash collected upfront for a service delivered later), which flows directly into cash from operations but is not recognized in Net Income until the service is delivered. This cash flow benefit is a quality hallmark of the subscription model.
Caveats and Alternative Interpretations: The primary caveat for both companies is the growing threat of Generative AI and the risk of commoditization. Will AI tools erode Adobe’s margins or pricing power? Will open-source or AI-powered design tools threaten AutoCAD’s lock-in? The market multiple may already reflect this risk, or it may be completely underestimating it. The valuation challenge lies in modeling the durability of their moats against this technological disruption. How to Do This Yourself (The Reverse DCF)The reverse DCF is the essential tool for sanity-checking a high-multiple stock. We will use it on Adobe ($ADBE), assuming current market values as of October 2025. Data to Gather and Checks
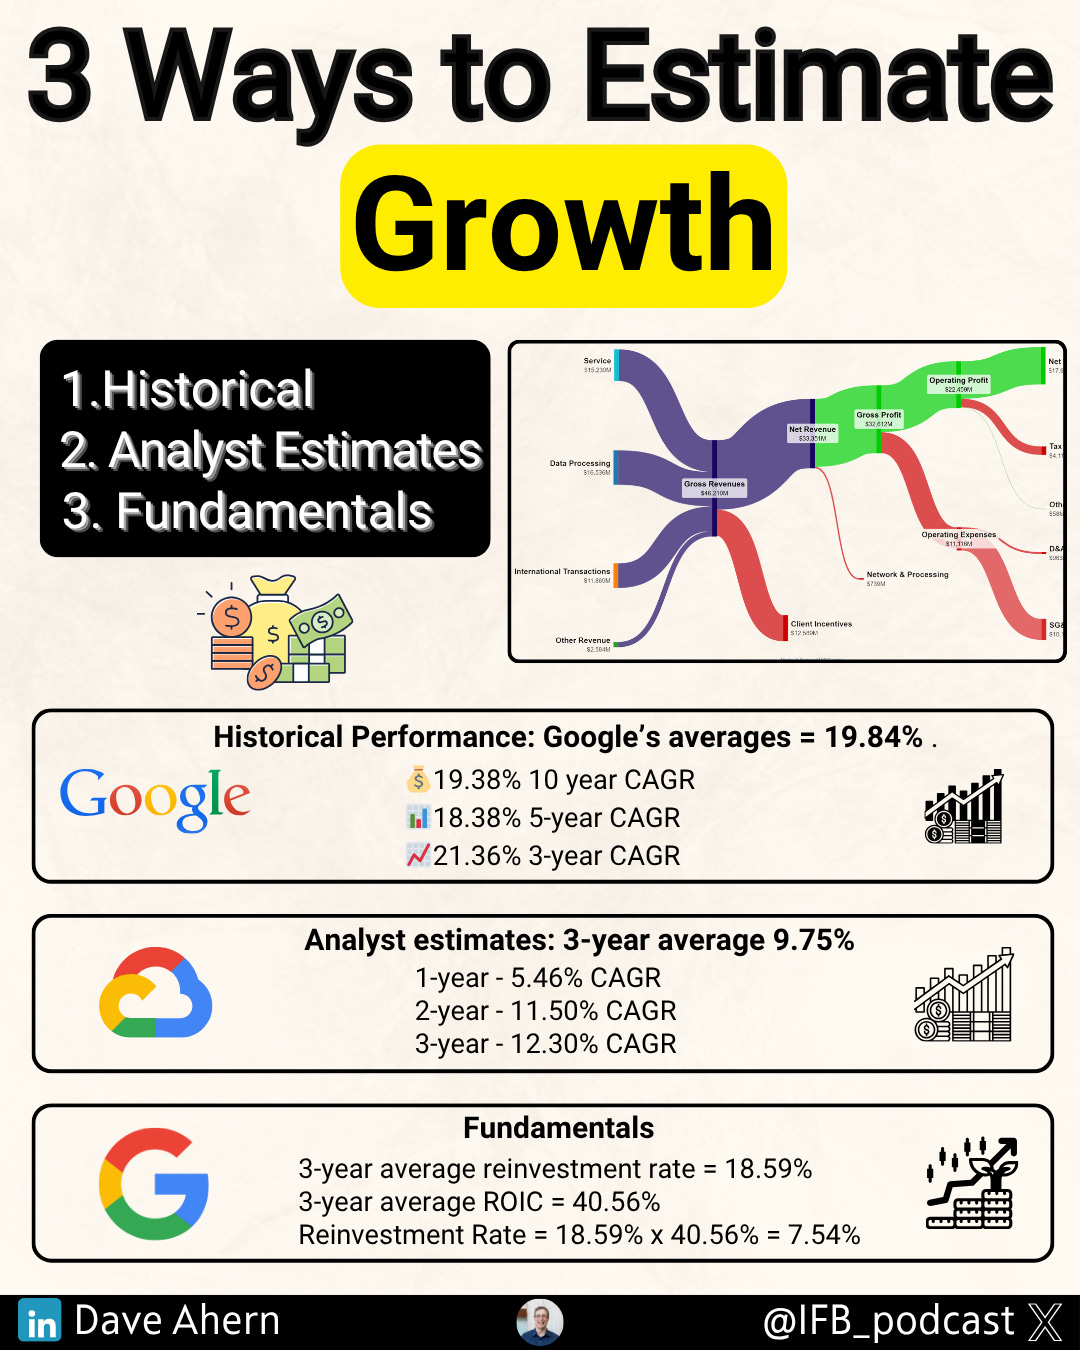
Exact Checks/Calculations: The Reverse DCF SetupWe will solve for the implied Revenue Growth Rate (implied) for a 10-year forecast period, maintaining a constant FCF Margin and using a reasonable terminal growth rate. Assumptions (For the Reverse DCF on Adobe):
The Iteration: By iteratively running a DCF model, we find the growth rate that makes the present value of all future cash flows equal to the current EV.
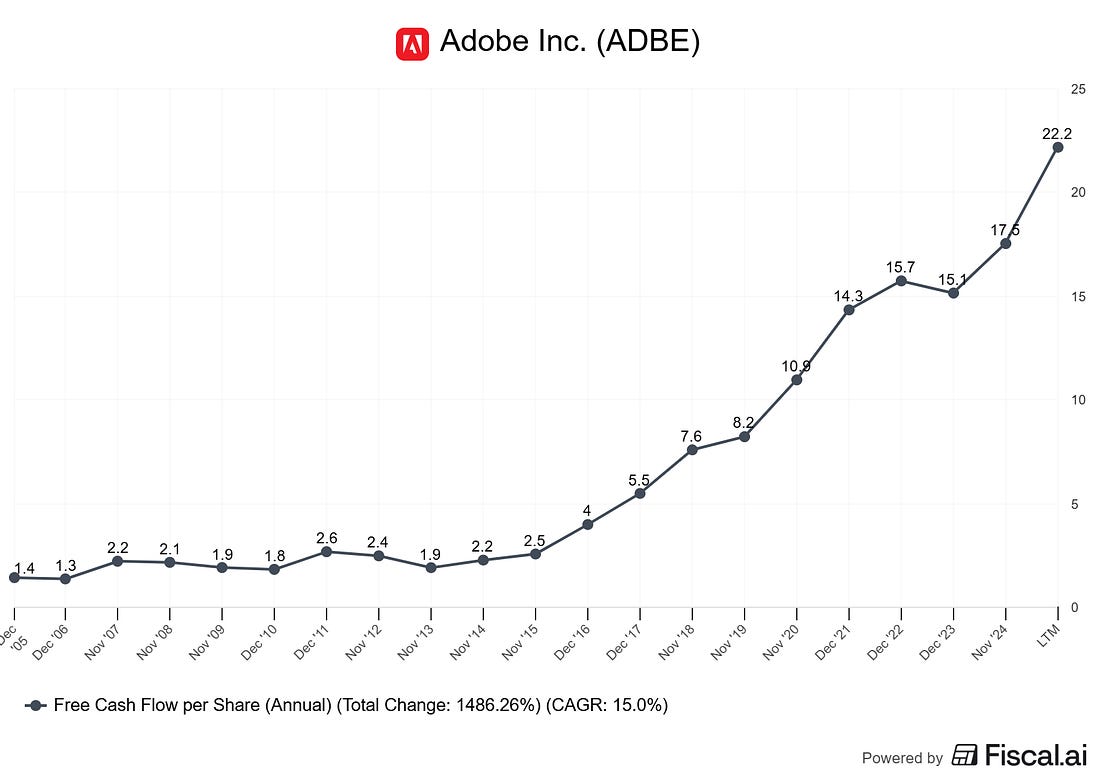
Result: To justify its current ~$200 Billion EV, Adobe must deliver an average 12.5% Free Cash Flow (and, by extension, Revenue) growth rate for the next 10 years, then grow at 3.0% forever after. Decision Rules and Thresholds
Pitfalls and False Positives1. The “Non-Cash” Trap (Stock-Based Compensation): SBC is often touted as a non-cash expense that can be ignored. This is a crucial mistake for a quality investor. SBC is an economic expense and a cash drain—it causes dilution, which is like a hidden tax on existing shareholders. If management repurchases shares to offset dilution, that requires real cash from the FCF we are valuing. Always treat SBC as an economic expense. 2. Mistaking Deferred Revenue for a Moat: Deferred revenue (cash collected upfront) is a great sign of stickiness and predictability, but it’s an accounting timing benefit for FCF conversion, not a true competitive moat. The moat is what drives customers to pay upfront (e.g., high switching costs or a superior product). 3. Terminal Value Over-Reliance: In the DCF, the Terminal Value (the value of the company after the explicit forecast period) can account for 60% to 80% of the total present value. This is why the Terminal Growth Rate (g) and the final year’s FCF assumptions are so crucial. Small changes here have a massive impact. Quality investing aims to find companies with durable moats that justify a higher-than-average terminal growth rate (e.g., 3.0% instead of 2.0%). Checklist / One-Pager
Glossary
Further Reading
References
Educational content, not investment advice. You're currently a free subscriber to School of Investing. For the full experience, upgrade your subscription.
|
Monday, November 10, 2025
Subscription Software Showdown: A Quality Investor’s Guide to Valuing Adobe vs. Autodesk




Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment