When a company’s revenue swings from COVID-driven peaks to normalized troughs, how do you separate signal from noise? Thermo Fisher Scientific (NYSE: TMO) offers a masterclass in scenario analysis — a $200B life sciences giant whose earnings fluctuated wildly as pandemic tailwinds faded. By anchoring valuation to mid-cycle metrics like EV/EBIT, FCF margin, and ROIC, you can build scenarios that reveal whether today’s price reflects temporary weakness or permanent impairment. Let’s learn how. TL;DR
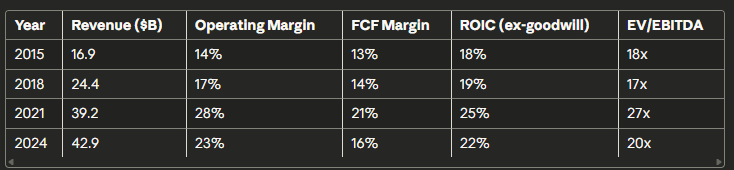
Why It MattersMost investors anchor to the numbers in the latest earnings report. Revenue down 2%? Sell. EPS up 8%? Buy. This reflex ignores cyclicality, one-time tailwinds, and mean reversion. Scenario analysis forces you to think probabilistically and normalize for cycles. Base rates: Over the last five years, Thermo Fisher shares have typically traded at EV/EBITDA multiples within 18-23x, but this range obscures dramatic swings. At its peak in 2021, COVID-related revenue contributed about 25% to the company’s total revenue, contributing some $2.5 billion. By 2024, this dropped to just $100 million per quarter, creating a 300 basis point growth headwind. Investors who valued TMO on 2021 peak earnings paid 27x EV/EBITDA for unsustainable margins. Where investors go wrong: They conflate cyclical peaks with structural earnings power. A company generating 20% operating margins at the top of a cycle may only sustain 15% mid-cycle. Valuing the peak at 25x EV/EBIT produces a disaster when margins compress and multiples contract simultaneously. Scenario analysis mitigates this by modeling multiple futures and weighting them by probability.
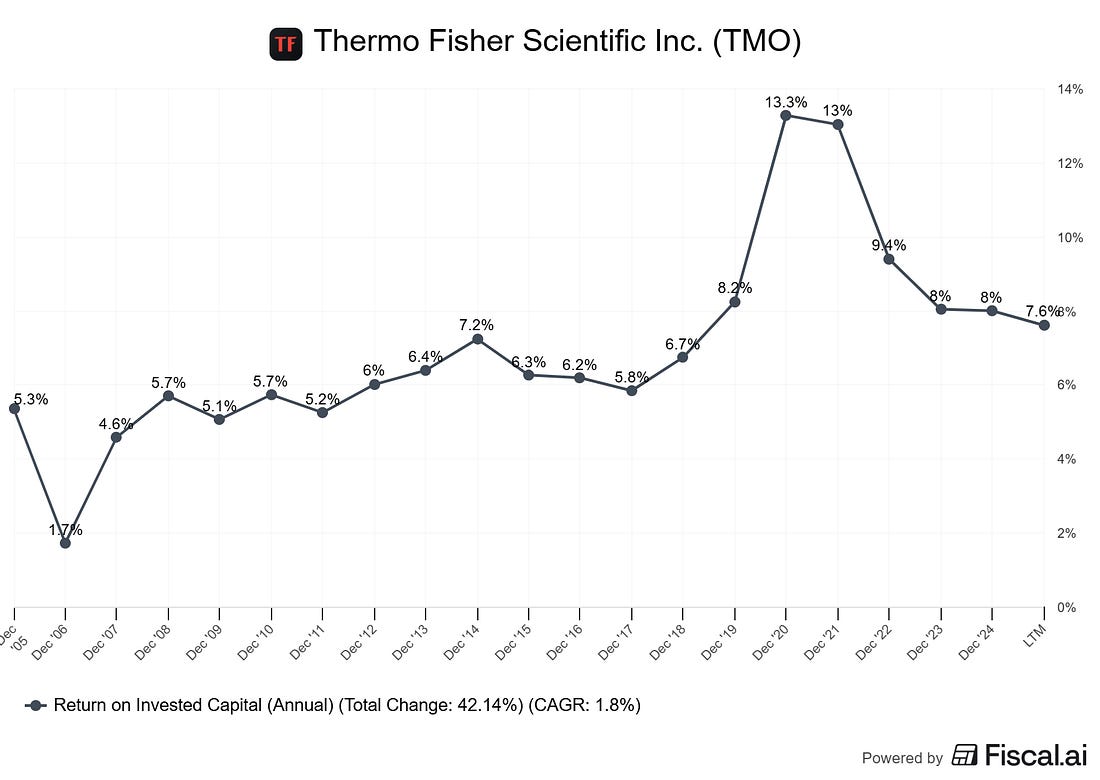
Core Concepts: Quality Investing Meets Scenario DesignROIC vs. WACC: The Value Creation EngineReturn on Invested Capital (ROIC) measures how efficiently a company converts capital into operating income. When ROIC exceeds Weighted Average Cost of Capital (WACC), the company creates value; when ROIC falls below WACC, it destroys value. As of May 2025, Thermo Fisher Scientific’s ROIC was 8.08% with a WACC of 8.96%, suggesting value destruction on the surface. But this headline figure is misleading. ROIC ex-goodwill provides insight into the company's ongoing capital efficiency. By removing the surplus (goodwill) from past M&A transactions, TMO is able to generate 22% returns on the capital invested in the business. This 13+ percentage point gap matters enormously — TMO’s acquisitions carry goodwill that depresses reported ROIC, but the underlying business generates exceptional returns. Decision rule: For serial acquirers like TMO, always calculate ROIC ex-goodwill to see economic reality. Demand a spread of ROIC – WACC > 5% sustained over multiple years before assuming durable value creation.
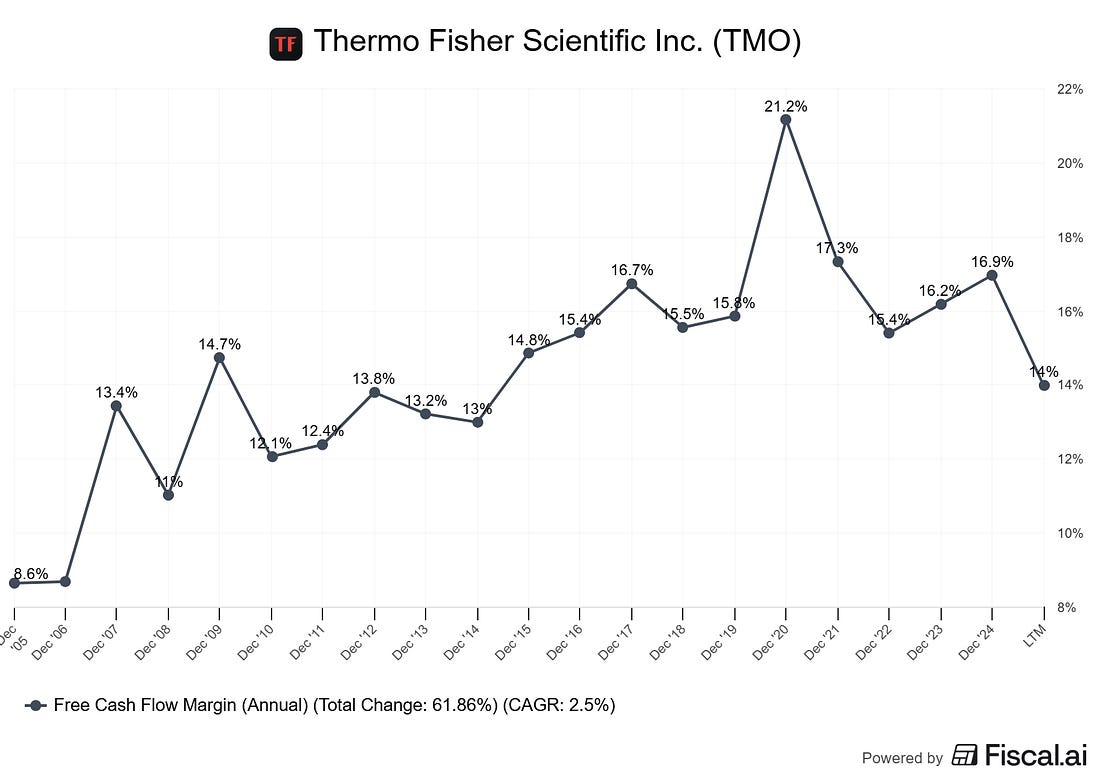
FCF Margin and Conversion: The Cash Reality CheckFree Cash Flow (FCF) margin — FCF divided by revenue — tells you how much of each sales dollar converts to discretionary cash. High-quality compounders typically sustain FCF margins of 15%+ and FCF conversion (FCF/Net Income) above 100%. For what it’s worth, TMO’s free cash flow have remained steady after COVID-19 and have remained around the $7 billion mark. These are very healthy levels at an FCF margin of around 16-17%. This stability through the cycle is remarkable — even as COVID revenues evaporated, TMO’s cash engine held firm. Evidence of pricing power and cost discipline.
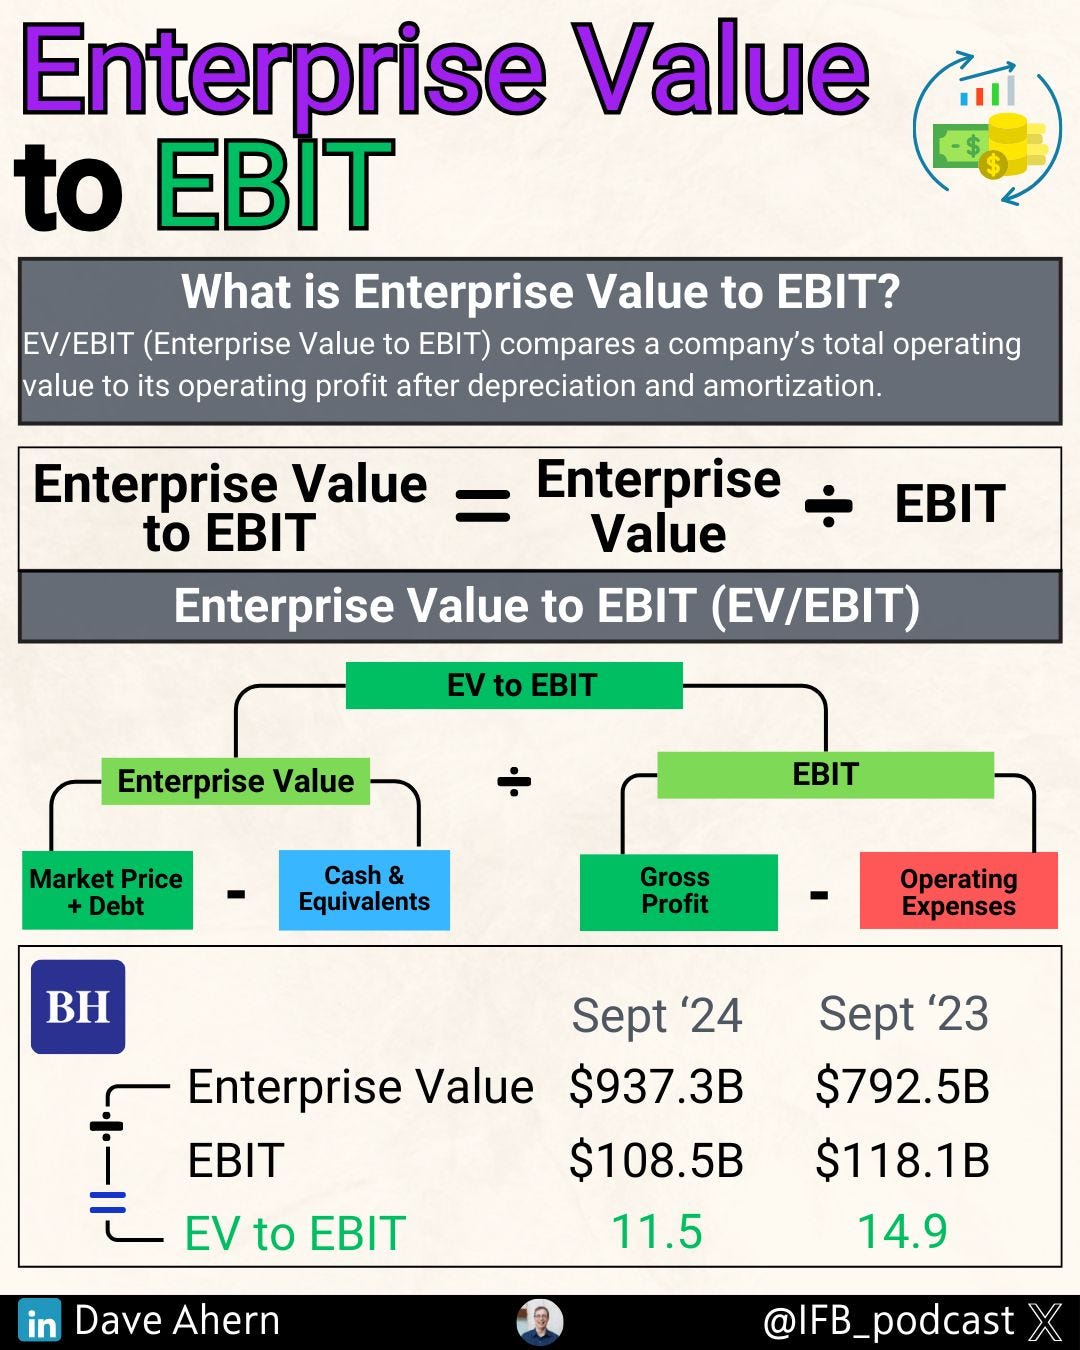
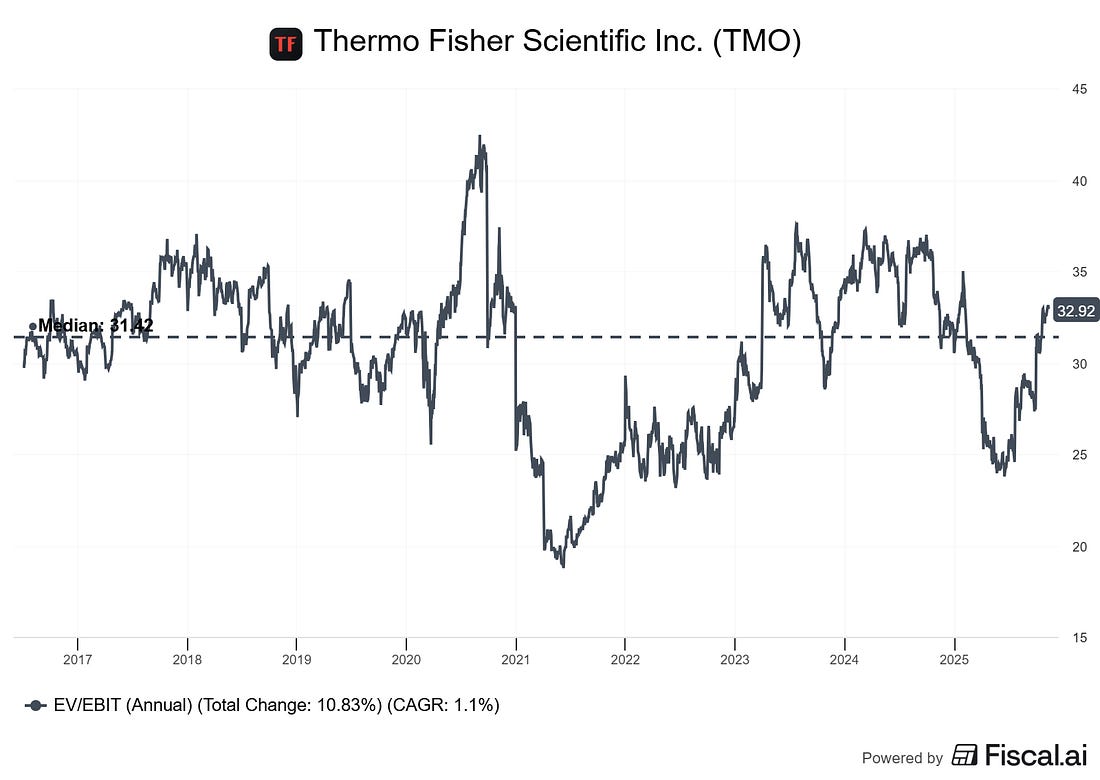
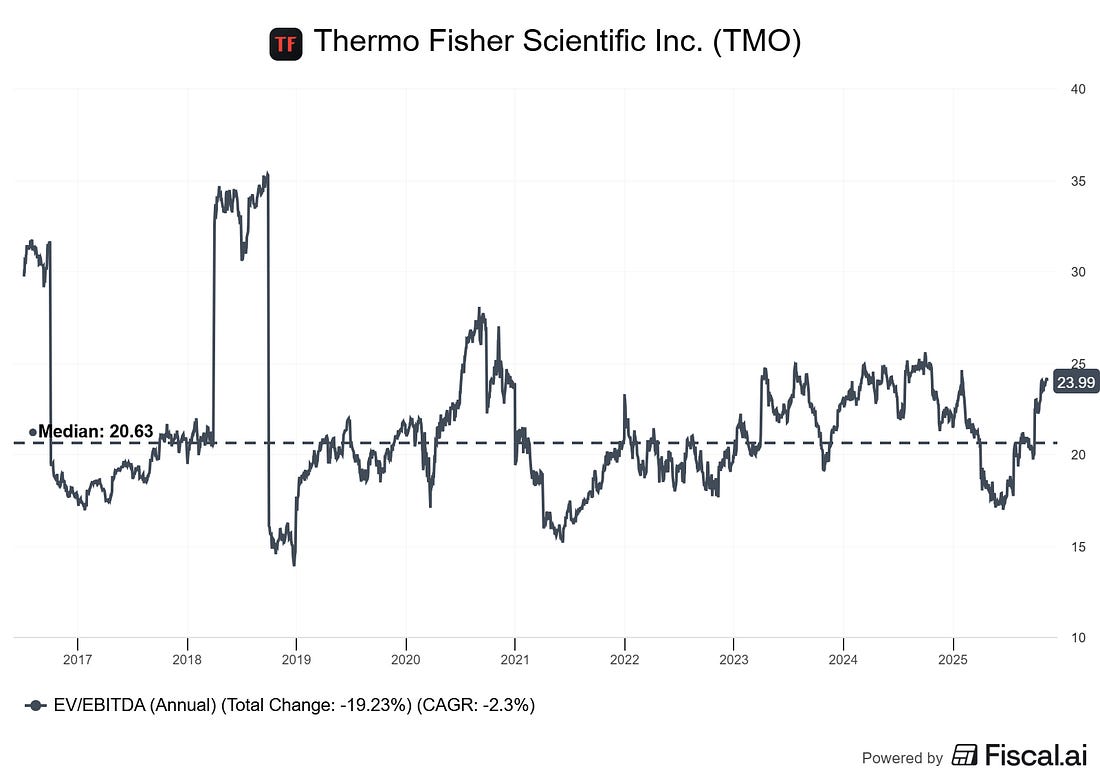
EV/EBIT and Valuation Multiples: The Market’s Price TagEnterprise Value to EBIT (or EBITDA) measures how much investors pay for each dollar of operating profit. It’s superior to P/E for capital-intensive businesses or serial acquirers because it accounts for debt and excludes depreciation and amortization distortions. During the past 13 years, the highest EV-to-EBITDA of Thermo Fisher Scientific was 27.47. The lowest was 15.00. And the median was 19.96. Currently, Thermo Fisher’s EV-to-EBITDA for today is 19.58, sitting near the historical median despite a growth slowdown. Valuation framework for scenarios: Use historical multiple ranges as guardrails. Bear case = low end of range (15-18x), base case = median (19-21x), bull case = high end (22-25x). Multiples should reflect expected growth and ROIC sustainability — a company growing at 3% with 8% ROIC doesn’t merit 25x EV/EBIT, but one growing at 7% with 20% ROIC does.
Scenario Design: Bear, Base, BullScenario analysis requires three inputs for each case:
Bear scenario: Assumes modest organic growth (1-2%), margin compression to cycle lows, and multiple contraction to the 25th percentile of the historical range. Base scenario: Assumes mid-cycle economics — normalized margins, steady-state growth in line with industry, and median historical multiple. Bull scenario: Assumes margin expansion from operating leverage, above-market growth from share gains, and premium multiple justified by ROIC superiority. Critical nuance: Weight scenarios by probability. If you assign 20% bear, 60% base, 20% bull, the probability-weighted valuation may sit 10-15% below the base case alone. This builds in conservatism. Worked Example: Thermo Fisher’s Cash EngineLet’s build scenarios for TMO as of November 2025 using a 3-year horizon (through 2028). Step 1: Establish the BaselineFY 2024 financials (actual):
FY 2025 guidance (management):
Key normalization: 2024 still carried ~$400-500M of COVID revenue. 2025 marks the first “clean” year. Management expects to exit 2025 near the low end of their 7-9% long-term organic growth target. Step 2: Build Three ScenariosBear Scenario (20% probability)Assumptions:
Math:
Base Scenario (60% probability)Assumptions:
Math:
Bull Scenario (20% probability)Assumptions:
Math:
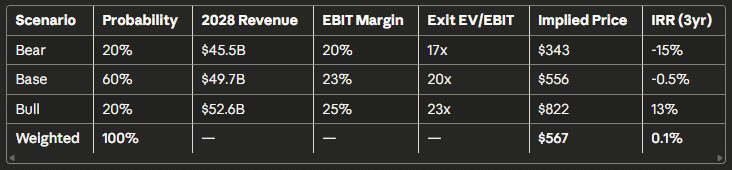
Step 3: Weight the OutcomesProbability-weighted value = (0.20 × $343) + (0.60 × $556) + (0.20 × $822) = $567/share Current price (November 2025): ~$565/share Interpretation: TMO trades at fair value using mid-cycle assumptions. The 20% downside to the bear case ($343) versus 45% upside to the bull case ($822) creates asymmetry, but the base case dominates at 60% weight. There’s no screaming bargain here, but no obvious overvaluation either. The setup rewards patient holders betting on margin expansion and organic growth acceleration. [Table: TMO Scenario Analysis Summary]
Step 4: Sanity ChecksROIC sustainability: ROIC ex-goodwill of 22% supports premium multiples if growth resumes. In the base case, 5% growth × 22% ROIC = 1.1% annual value creation per share (ROIC × reinvestment rate). This justifies a 20x EV/EBIT multiple. FCF conversion: FCF margin of 16-17% on $50B revenue = $8B+ FCF by 2028. Base case assumes $17% × $49.7B = $8.4B FCF, which funds $3B buybacks and $1B dividends, with $4.4B for debt paydown or M&A. Check: Reasonable. Historical valuation bands: TMO’s 10-year EV/EBITDA range of 15-27.5x (median 20x) aligns with our bear (17x EV/EBIT ≈ 15x EV/EBITDA) and bull (23x EV/EBIT ≈ 21x EV/EBITDA) exit multiples. Check: Within bounds. [Table: Historical TMO Margin Trends (2015-2024)]
Source: Company 10-Ks, GuruFocus data as of Nov 2025 How to Do This YourselfData to Gather
Step-by-Step ProcessStep 1: Normalize earnings. Identify cyclical peaks/troughs. For TMO, 2021 was the peak (COVID boost), and 2024 is normalized. Use 3-5 year averages for mid-cycle margins if unsure. Step 2: Define growth assumptions. Bear = 1-2% below trend, Base = company guidance or industry growth, Bull = 1-2% above trend. Cross-check with historical CAGRs. Step 3: Set margin assumptions. Map operating margin to historical percentiles. Bear = 25th percentile, Base = median, Bull = 75th percentile. Adjust for structural changes (e.g., TMO’s margin expansion from PPI productivity system). Step 4: Choose exit multiples. Use 10-year range for EV/EBIT or EV/EBITDA. Bear = 25th percentile, Base = median, Bull = 75th percentile. Tighten ranges for stable businesses, widen for cyclicals. Step 5: Model balance sheet. Assume FCF after dividends funds either buybacks (accretive) or debt paydown (reduces EV). Update the share count annually at ~1-2% per year for quality compounders. Step 6: Calculate terminal EV and equity value. For each scenario: Terminal EV = EBIT × Exit Multiple. Equity value = EV – Net Debt. Price per share = Equity Value / Shares Outstanding. Step 7: Weight scenarios. Assign probabilities (e.g., 20/60/20). Calculate the weighted average price. Compare to the current price for the implied margin of safety. Decision Rules and Thresholds
Pitfalls and False PositivesPitfall 1: Anchoring to peak earnings and valuing a company at 20x EBIT when EBIT is at a cyclical high guarantees overpayment. Always normalize to mid-cycle. Pitfall 2: Ignoring goodwill in ROIC. Serial acquirers like TMO carry significant goodwill, which depresses reported ROIC. Calculate ROIC ex-goodwill to see the economic reality. Pitfall 3: Static multiples across scenarios. Multiples should flex with growth and ROIC. A bear case with 2% growth and 15% ROIC doesn’t deserve a 22x EV/EBIT multiple. Pitfall 4: Overweighting the bull case. Human psychology is optimistic. Discipline yourself: 20% bull, 60% base, 20% bear is a reasonable default. Adjust only with strong evidence. Pitfall 5: Ignoring capital allocation. A company buying back stock at peak valuations destroys value. Check historical buyback prices relative to intrinsic value. False positive: High FCF margin with falling ROIC. A company can juice FCF by slashing capex, but this kills future growth. Always pair FCF margin analysis with ROIC trends. False positive: Compressed multiple “on the cheap.” A stock trading at 15x EV/EBIT (below its 20x median) isn’t cheap if ROIC is collapsing and growth is turning negative. Multiples compress for a reason. Checklist
Glossary
Further Reading
Disclaimer: Educational content, not investment advice. You're currently a free subscriber to School of Investing. For the full experience, upgrade your subscription.
|
Monday, November 24, 2025
How to Value Thermo Fisher Through the Cycle: A Scenario Analysis Framework Using EV/EBIT and ROIC




Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment