Novo Nordisk has become a household name, but behind the headlines about Ozempic and Wegovy lies a powerful financial engine. Today’s post delves into the accounting reality of a company firing on all cylinders, illustrating how its exceptional gross margins and reinvestment in manufacturing capacity create a durable competitive advantage that investors can track through the financial statements. TL;DR
Why It Matters: Beyond the NarrativeIt's easy to be captivated by the story of a company changing the world with blockbuster drugs. But great narratives don't always translate into great investments. For investors, the real story is told in the financial statements. Understanding the interplay between pricing power (gross margins), reinvestment needs (capital intensity), and competitive durability (the moat) is what separates speculation from analysis.
Investors often go wrong by focusing solely on revenue growth while ignoring the underlying unit economics and capital required to achieve that growth. A company that grows revenues by 50% but sees its Return on Invested Capital (ROIC) fall below its cost of capital is destroying value, not creating it. Novo Nordisk presents a fascinating case where explosive growth is matched by world-class profitability and a deliberate, massive reinvestment cycle. This is where we can see quality investing principles in action. Core Concepts: The Quality Investor's ToolkitTo dissect a company like Novo Nordisk, we need the right tools. This isn't about complex models; it's about understanding the fundamental drivers of value creation. ROIC vs. WACC and Value CreationThe single most important measure of a business's quality is its Return on Invested Capital (ROIC). It tells you how much profit the company generates for every dollar of capital it has invested in its operations (both debt and equity). The Weighted Average Cost of Capital (WACC) is the blended cost of that capital. A business creates value only when ROIC > WACC. The wider the spread, the more value is created. Reinvestment Runway and Capital IntensityA high ROIC is great, but for a company to compound its value over time, it must be able to reinvest its profits back into the business at similarly high rates. This is the "reinvestment runway." We measure this by examining capital expenditures (CapEx) and research and development (R&D) spending. Capital Intensity tells us how many dollars of assets are required to generate a dollar of sales. For a pharmaceutical company, this includes capital expenditures (CapEx) and research and development (R&D) expenses. From GAAP Net Income to Owner EarningsNet Income is an accounting opinion. Free Cash Flow (FCF), also known as "Owner Earnings," is the cash remaining for shareholders after all expenses and necessary reinvestments have been paid. The bridge is crucial:
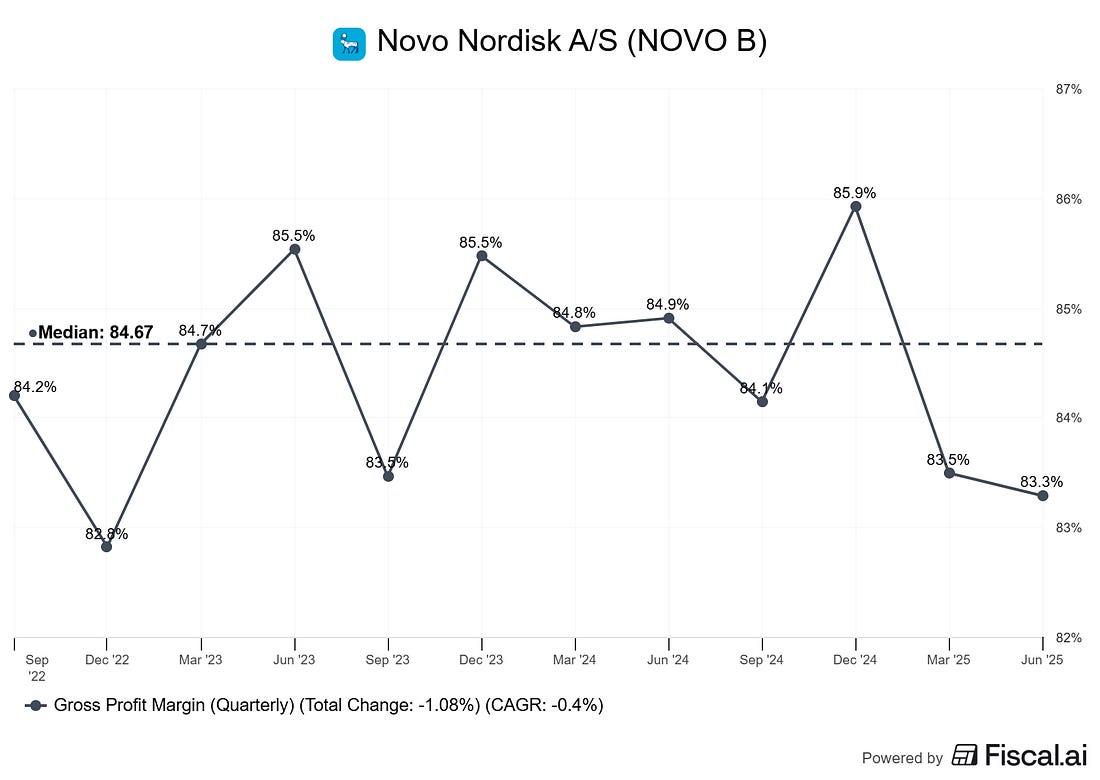
Moat Durability and EvidenceA moat is a structural competitive advantage that protects those high returns (ROIC). We don't listen to management claims; we look for evidence in the numbers. Sustained high gross margins (>60%), stable operating margins, and a consistently wide ROIC-WACC spread are quantitative proof of a moat. For Novo, this comes from its patents, brand recognition, and complex manufacturing process. Case Study: Novo Nordisk (NOVOB DC)Novo Nordisk is a Danish pharmaceutical giant founded in the 1920s, historically focused on diabetes care. Its recent development of GLP-1 agonists—first for diabetes (Ozempic) and later for obesity (Wegovy)—has caused an explosion in demand, revenue, and market value. The Margin of VictoryThe first place to look for evidence of a moat is the gross margin. It reflects the company's pricing power. Novo's is simply staggering.
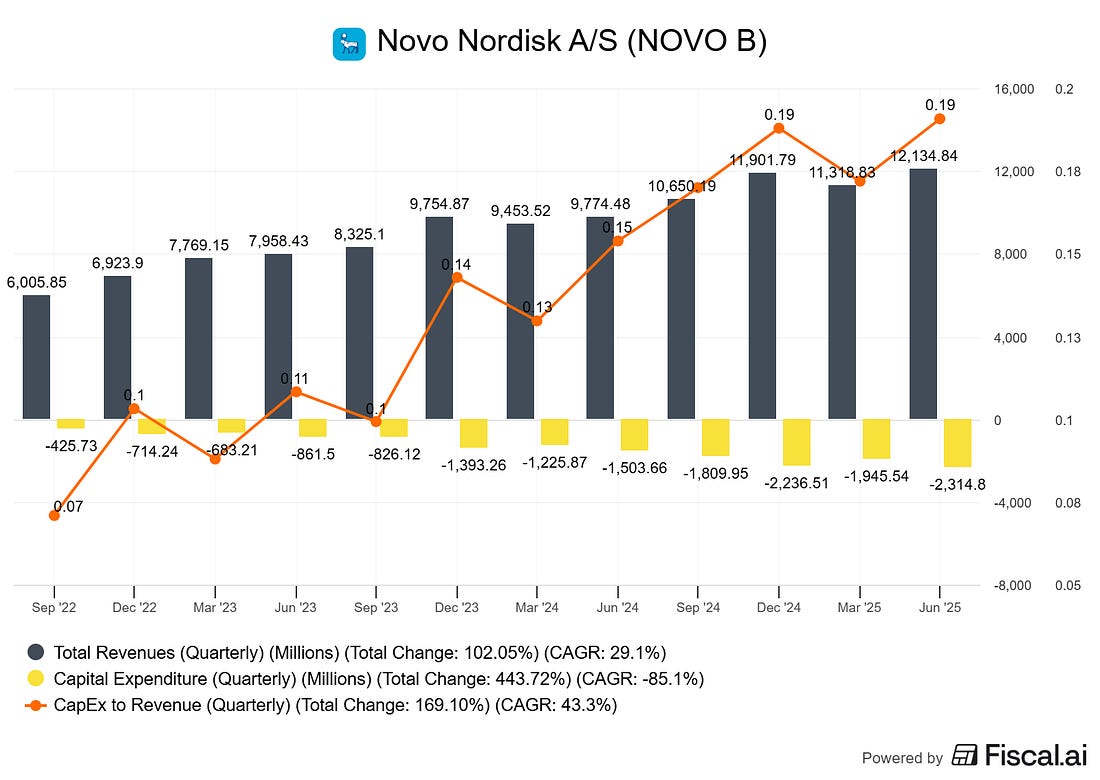
An 84%+ gross margin means that for every $100 of product sold, the direct cost of producing it (materials, factory labor) is less than $16. This leaves a substantial amount of gross profit to fund R&D, sales, and marketing, while still delivering exceptional operating profits. Reinvestment to Meet a RevolutionThe GLP-1 drugs created a problem every company dreams of: demand far outstripping supply. To solve this, Novo is reinvesting at an unprecedented rate. In its 2023 Annual Report, the company projected capital expenditure of around DKK 45 billion (approximately $6.5 billion USD) for 2024, a significant increase from prior years (Novo Nordisk, 2024).
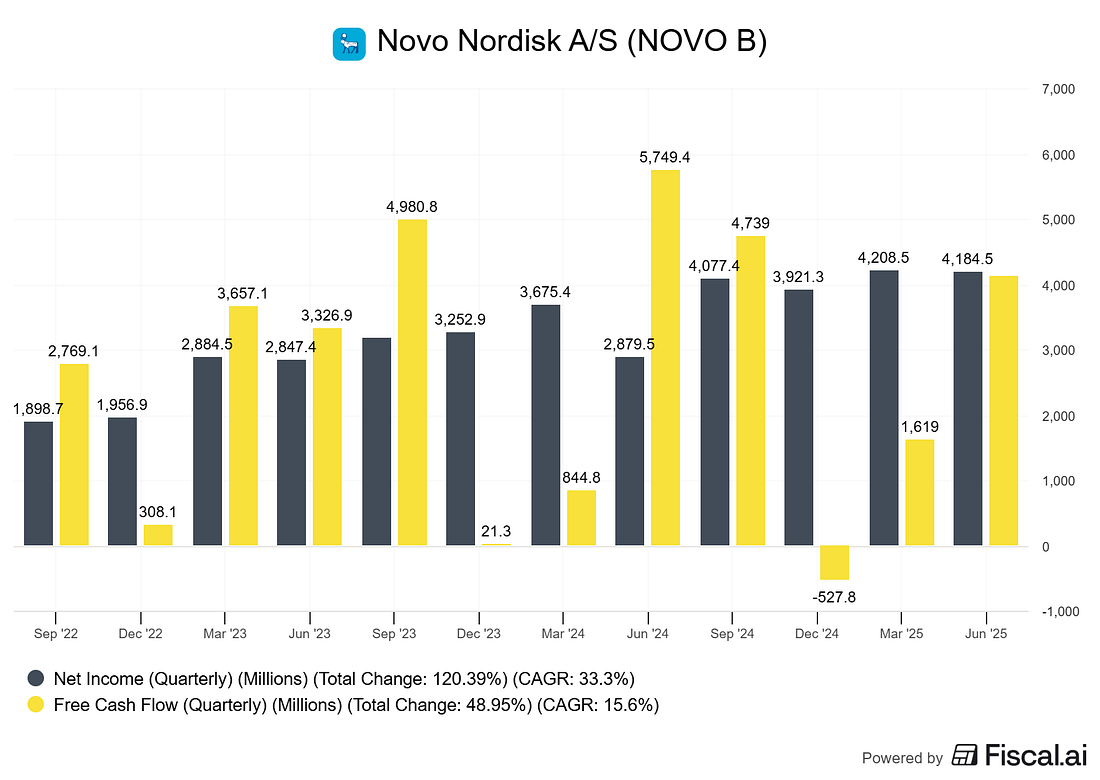
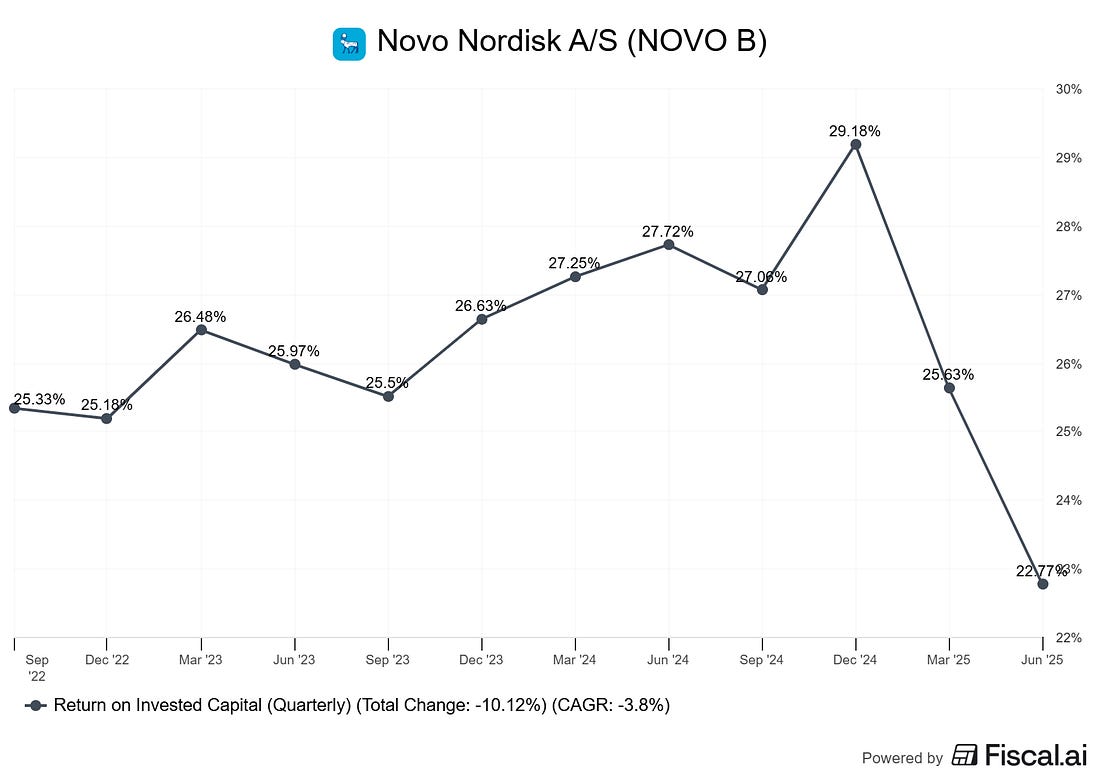
This spending directly impacts FCF. Let's build a simplified bridge from GAAP earnings to Owner Earnings to see this effect. A reconciliation showing 2023 Net Income (DKK 83.7B), adding back D&A (DKK 13.9B), subtracting Change in WC (DKK -1.5B, a source of cash), and subtracting CapEx (DKK 26.1B) to arrive at a simplified FCF (DKK 73.0B). Note: Numbers are illustrative based on reported figures. This bridge illustrates that while Net Income is a substantial number, the cash available to owners is reduced by the significant investment in future growth. The FCF conversion rate (FCF/Net Income) was approximately 87% in 2023. This is still healthy, but lower than in previous years, a direct result of the capital expenditure increases. ROIC: The Ultimate ScorecardDespite the heavy investment, Novo's profitability is so high that its ROIC remains in a league of its own.
A ROIC consistently above 20-30% is extraordinary. It means the business is a compounding machine. The key question for the future is whether the returns on the new capital being invested in factories will be as high as the returns on the existing capital base. Given the unmet demand, the answer for the medium term appears to be yes. Per-Share FramingGrowth is only valuable to shareholders if it translates to per-share value. Novo has a strong track record of returning capital to shareholders via dividends and buybacks, which reduces the share count over time. How To Do This Yourself: A Step-by-Step Guide
Pitfalls and False Positives
Checklist: Case Study Analysis
Glossary
Further Reading
References
Educational content, not investment advice. You're currently a free subscriber to School of Investing. For the full experience, upgrade your subscription.
|
Saturday, September 27, 2025
Novo Nordisk: A Case Study in Gross Margins, Moats, and Manufacturing Muscle




Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment