Welcome to the Free edition of How They Make Money. Over 200,000 subscribers turn to us for business and investment insights. In case you missed it: Every advanced piece of technology, from a supercomputer to a smartphone, is a marriage of two distinct functions: logic and memory.
While we recently discussed the new Intel x NVIDIA deal in the world of logic, AI demand is also creating a boom for memory. Micron’s Q4 earnings just gave us the clearest signal yet. Let’s review what we learned. At a glance:
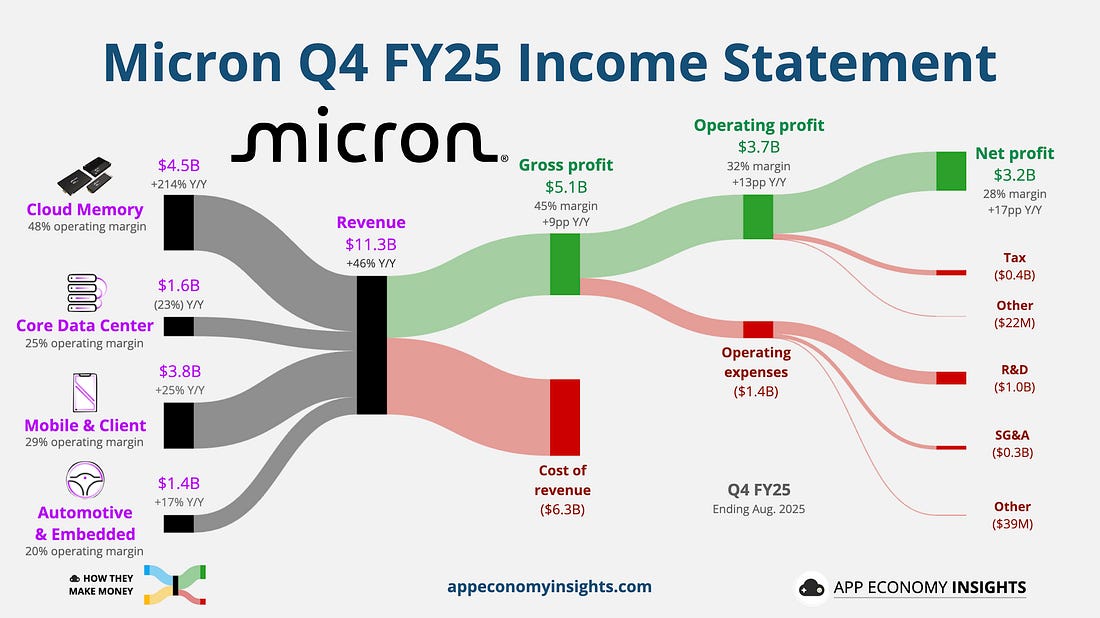
1. Micron’s new business unitsMicron is a US-based Integrated Device Manufacturer (IDM), like Intel, but focused on designing and manufacturing memory chips. Starting with Q4 FY25 (August quarter), Micron reorganized its entire business into four business units that mirror how customers actually buy memory chips.
This split is designed to make Micron’s business easier to understand. It makes the economics of the all-important AI memory (HBM) business more transparent and should reduce the “lumpiness” in their quarterly results. The only catch with the new segmentation? Year-over-year comparisons will be a bit messy for a while. Keep an eye out for when Micron releases restated historical data to make sense of the new segments. This new structure gives us a perfect lens to view the most important story in the memory market today: the dramatic AI-driven cycle.
Market reaction was timid. Micron’s stock (MU) has nearly doubled so far in 2025. Wall Street’s expectations were so high that even a great report was seen as a slight letdown. This highlights the frenzy and optimism already priced into the stock. 2. The HBM-powered recovery
Why it matters
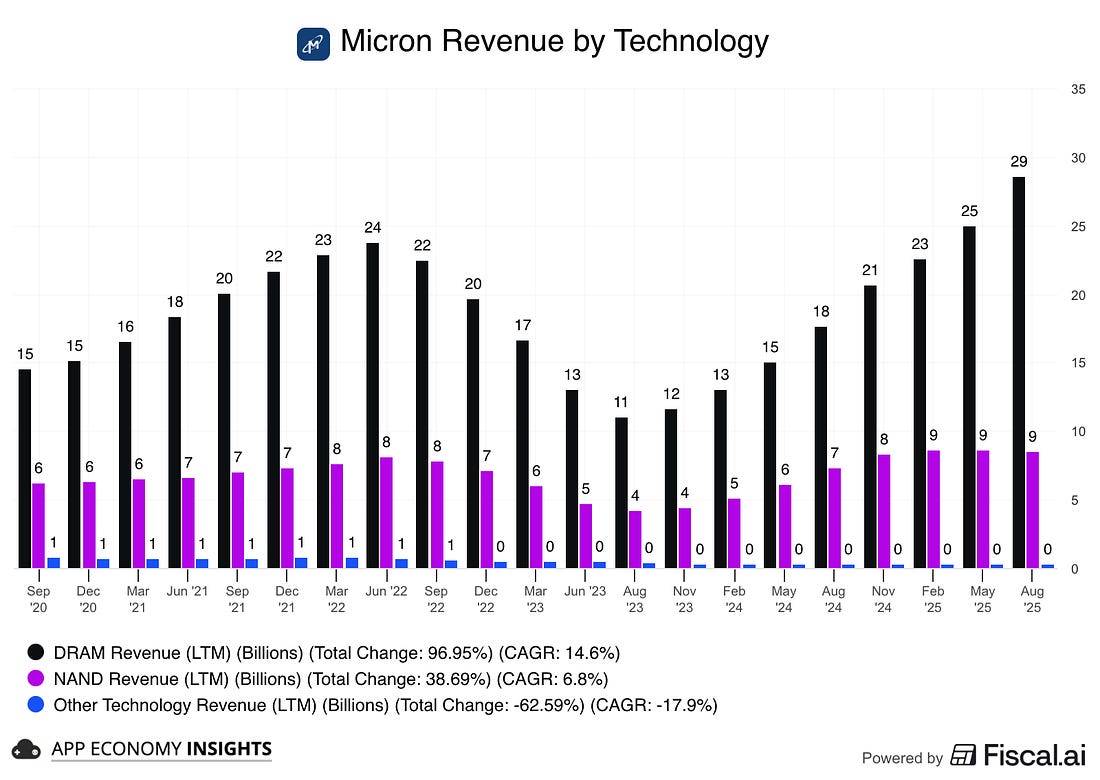
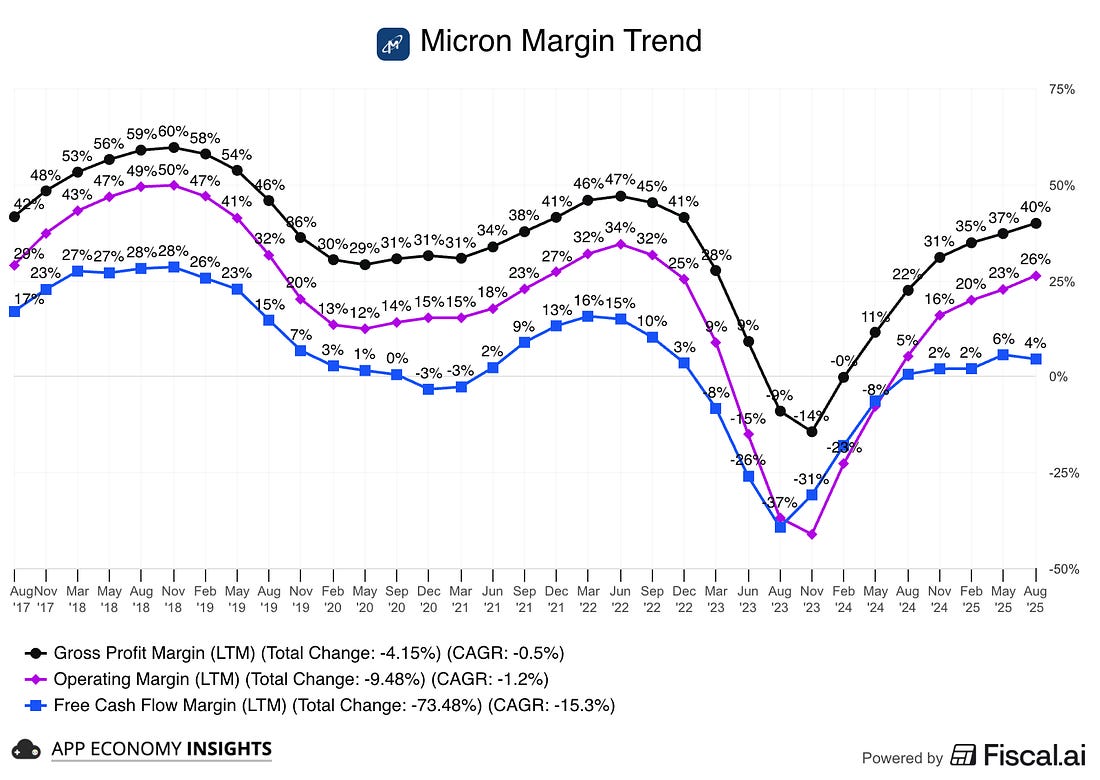
The memory up-cycle is here, led by HBM-driven DRAM. Micron’s new segment split reveals a clear path to higher profitability. As the mix shifts toward premium HBM products, it should raise the company’s gross margin ceiling, potentially breaking the boom-and-bust cycles of the past (see visual).
Micron’s print confirms memory remains the gating factor for AI systems in the near term. HBM inventory is tight, and gross margin is tracking to cross 50%. 3. Key quotes from the earnings callCheck out the post-call Q&A on Fiscal.ai here. CEO Sanjay Mehrotra on momentum:
AI data-center memory is now a franchise line, not an experiment. It’s lifting the entire data center market. It shows that the recovery is broad-based and adds another powerful (and somewhat unexpected) tailwind to the Micron story. On competition:
Micron and SK Hynix have gained a first-mover advantage against market leader Samsung by being faster to market with the latest generations of HBM.
Supply-chain and policy angle can resonate with US hyperscalers. On HBM customer concentration:
Micron expanded its customer base from four in Q3 to six in Q4. And they are essentially sold out of their premium product more than a year in advance. It underscores the desperation of AI companies to secure memory supply. This is a real up-cycle, not a one-quarter blip. CFO Mark Murphy on expectations:
Murphy is making the case that strong profitability is set to continue, justifying the high expectations. However, the company notably declined to comment on whether HBM margins specifically would remain at today’s level. 4. What to watch moving forwardThe memory up-cycle is in full swing, so here’s what to watch as the story unfolds. Key metrics
Potential risks
The investor viewUltimately, two clear narratives have emerged:
The story is clear: a structural shift to high-margin HBM is underway. The data center business has shattered its old ceiling (growing from a third of overall revenue to more than half), proving that AI has reset the memory playbook. This up-cycle could raise the industry’s margin floor and smooth future swings. But remember, cycles don’t vanish. In investing, the most dangerous words are “it’s different this time.”
That's it for today. Happy investing! Want to sponsor this newsletter? Get in touch here.Thanks to Fiscal.ai for being our official data partner. Create your own charts and pull key metrics from 50,000+ companies directly on Fiscal.ai. Start an account for free and save 15% on paid plans with this link. Disclosure: I own AMD, ASML, and NVDA in App Economy Portfolio. I share my ratings (BUY, SELL, or HOLD) with App Economy Portfolio members. Author's Note (Bertrand here 👋🏼): The views and opinions expressed in this newsletter are solely my own and should not be considered financial advice or any other organization's views. I would love to hear your feedback! Reply to this email to reach out to me with questions or suggestions. If you enjoyed today's newsletter, please share it with your friends and family! You’ll earn rewards if they subscribe. You’re a free subscriber to How They Make Money. For the full experience, become a Premium subscriber.
|
Friday, September 26, 2025
☁️ Micron Rides the AI Boom





Subscribe to:
Post Comments (Atom)
No comments:
Post a Comment